South Dakota Estate Accounting: A Representative's Guide
South Dakota probate runs through the circuit court, and its fiduciary is the personal representative, the executor named in a will or the administrator appointed when there is none. South Dakota is a Uniform Probate Code state, South Dakota Codified Laws Title 29A, and its Unified Judicial System publishes no form for a decedent's estate inventory, account or closing statement. The statute is the whole specification. Here is what it requires, the deadlines behind it, and how a South Dakota estate closes.
Section 1 of 7.The two documents: the Inventory and the Verified Statement
South Dakota administers decedents' estates under Codified Law 29A-3, Probate of Wills and Administration. SDCL 29A-1-201(8) defines court to mean the circuit court, so there is no separate probate court and no probate division the way some other states have. Every section behind this guide is written 29A-3-xxx.
The first document is the inventory, required by SDCL 29A-3-706. It is one list of the property the decedent owned at death, with reasonable detail, its fair market value as of the date of death, and the type and amount of any encumbrance against it. Furnishing a copy to anyone who asks is mandatory and has to happen promptly. Filing the original with the court is the personal representative's own option.
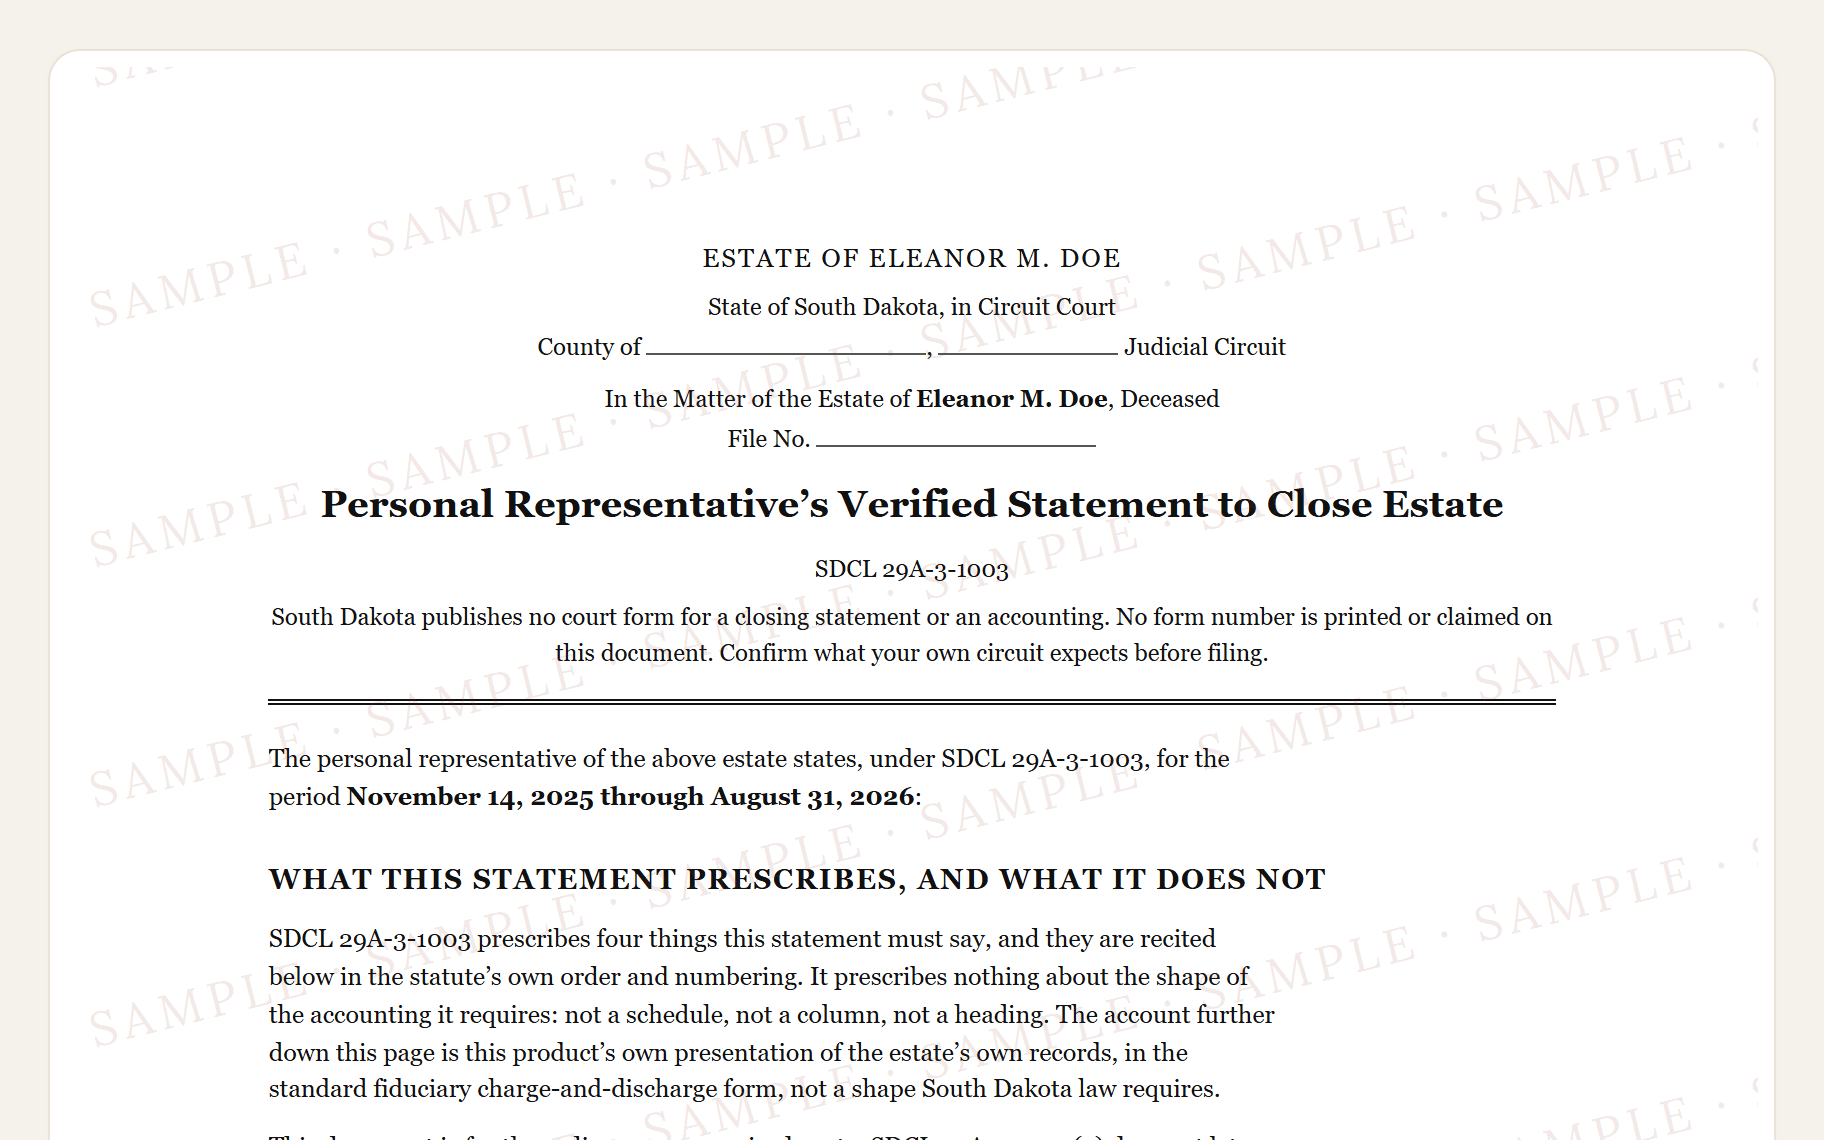
The second document is the closing statement, a verified statement filed under SDCL 29A-3-1003 once the estate is ready to close. It carries four recitals about creditors, taxes, administration and distribution, and copies of it and of a full accounting go to the people entitled to them. South Dakota's own accounting can be skipped entirely if everyone entitled to a copy consents in writing.
One warning worth stating plainly. The only inventory form the Unified Judicial System publishes is UJS-140, titled Initial Inventory. It is a conservatorship and guardianship form under chapter 5, sworn by a conservator, and it has nothing to do with a decedent's estate. A personal representative who finds it while searching the court's own site should not use it for a probate inventory.
Section 2 of 7.South Dakota's deadlines, with the statute behind each
- Day 14 (about 2 weeks)Notice of appointment to heirs and devisees
Why
Under SDCL 29A-3-705, the personal representative generally must send information of the appointment to heirs and devisees (and any devisees under an unprobated will) within 14 days after appointment; confirm the required recipient list and exact deadline with your attorney. - Day 14 (about 2 weeks)Notice to SD Department of Social Services (Medicaid estate recovery)
Why
Under SDCL 29A-3-705(c), the personal representative generally must send written notice of the appointment, including the decedent's Social Security number, to the South Dakota Department of Social Services within 14 days after appointment; confirm whether this applies to your estate and the exact deadline with your attorney. - Day 120 (about 4 months)Creditor claims bar date
Why
Under SDCL 29A-3-801, creditors generally must present claims by the later of four months after the personal representative's appointment or 60 days after written notice was mailed to a known creditor, and claims subject only to published notice are typically barred four months after first publication, so calendar the bar date before paying claims or distributing; confirm the operative bar date with your attorney. - Day 120 (about 4 months) · earliest possibleEarliest date to file a closing statement
Why
Under SDCL 29A-3-1003, for an unsupervised estate, the personal representative generally may not file the verified closing statement until at least four months after appointment; confirm your estate's eligibility for this informal closing route and the earliest allowable filing date with your attorney.
- Day 270 (about 9 months)Inventory and appraisement of estate property
Why
Under SDCL 29A-3-706, the personal representative generally must prepare an inventory of the decedent's property, with fair market values as of the date of death, within nine months after death (or six months after appointment, if that is later); confirm the exact controlling date with your attorney. - Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month extension may be available; confirm applicability and timing with your attorney.
The inventory is due within six months after appointment, or nine months after the decedent's death, whichever is later (SDCL 29A-3-706). This is later than the three-month deadline most other Uniform Probate Code states use, and several probate summaries online, including some written by AI, state three months for South Dakota anyway. That is wrong against the statute's own text. Both limbs matter, and the later of the two controls.
Read the full explanation
Property found after the inventory, or a value or description in the original that turns out to be erroneous or misleading, goes on a supplementary inventory under SDCL 29A-3-708. It is its own instrument, never added into the original's total, and the statute sets no deadline for filing it.
The closing statement may be filed no earlier than four months after the date of the original appointment of a general personal representative, not four months after death and not four months after a later successor's own appointment (SDCL 29A-3-1003(a)).
Once the closing statement is filed, and if no proceeding involving the personal representative is pending in the court a year later, the appointment terminates on its own (SDCL 29A-3-1003(b)).
Creditor claims run on two separate clocks. Publication is optional: once a week for three weeks in a legal newspaper in the county, and a claim not presented within four months after the first publication may be barred (SDCL 29A-3-801(a)). Written notice to a creditor known to, or reasonably ascertainable by, the personal representative is mandatory, and that creditor's claim is barred four months after appointment or sixty days after the notice was mailed or delivered, whichever is later (SDCL 29A-3-801(b)). An outside bar closes out any claim three years after the decedent's death regardless (SDCL 29A-3-803(a)(3)). Because the closing statement's four-month clock runs from appointment and the publication bar's four-month clock runs from first publication, the two do not start on the same day, so an estate that published late is not necessarily ready to close at the four-month mark.
A federal estate tax return, Form 706, if the estate needs one, is due nine months after death (IRC section 6075), with a possible six-month extension. Confirm whether the estate needs one with your attorney.
Section 3 of 7.What South Dakota pays a personal representative
SDCL 29A-3-719(a) sets reasonable compensation for a personal representative, and for any attorney, accountant, appraiser or other agent employed, weighed against seven factors: the time and labor involved, the novelty and difficulty of the questions and the skill required, whether taking the work precluded other employment, the fee customarily charged in the locality, the nature and value of the assets, the income earned and the responsibilities and potential liabilities assumed, the time limitations the circumstances imposed, and the experience, reputation, diligence and ability of the person performing the services. A will's own compensation clause may be renounced before qualifying, and a renunciation of fee may be filed with the court (SDCL 29A-3-719(b)).
When compensation is not set by will, or the estate is intestate, SDCL 29A-3-719(c) sets commissions on the personal property accounted for: 5 percent of the first $1,000, 4 percent of the next $1,000 to $5,000, and 2.5 percent of everything over $5,000. Real property accounted for by the personal representative is different: it earns just and reasonable compensation fixed by the court, not a percentage, and any real estate sold as part of the probate proceedings is treated as personal property for this purpose instead.
ExecutorLedger never computes a South Dakota commission from these percentages. Where the estate's own records show compensation already paid, that figure is what the closing statement reports, and nothing on the page claims a court has allowed or will allow it.
Section 4 of 7.How a South Dakota estate closes
SDCL 29A-3-1003(a) lets a personal representative close an estate, outside of supervised administration, by filing a verified statement with the court no earlier than four months after the date of original appointment of a general personal representative. That date is the earliest the statement may be filed, not a due date.
The statement carries four recitals, in the statute's own order. The first: either that the time limit for presenting creditors' claims has expired, or that a diligent search was made and the personal representative affirms that, to the best of their knowledge, information and belief, all known creditors have been paid in full and any others are unknown and could not, with reasonable diligence, be ascertained. The second: that all inheritance taxes and state estate taxes due from the estate have been determined and are fully paid. Both of South Dakota's death tax chapters were repealed by SL 2014, chapter 59, so this recital is satisfied at nil. It still has to print, so a reader is not left hunting for a tax that no longer exists. The third: that the estate has been fully administered, with payment, settlement or other disposition made of every properly presented claim and every expense of administration, and the assets distributed to the people entitled, except as the statement specifies. If any claim remains undischarged, the statement has to say either that the estate was distributed subject to possible liability with the distributees' agreement, or set out in detail what other arrangement was made. The fourth: that a copy of the statement and a full accounting were sent to every heir and devisee entitled to distribution, and to every known creditor and other claimant whose claim is neither paid nor barred.
SDCL 29A-3-1003(c) lets the accounting itself be waived if the people entitled to a copy consent in writing. That is not something every Uniform Probate Code state allows. If everyone entitled agrees in writing, a South Dakota estate can close without any accounting at all.
Once the statement is filed, SDCL 29A-3-1003(b) starts a one-year clock. If no proceeding involving the personal representative is then pending in the court, the appointment terminates on its own, with no order needed.
A supervised estate uses the formal route instead, under SDCL 29A-3-1001. The personal representative may petition for it after four months from the original appointment, and it is granted as a matter of course; any other interested person may petition after a year, granted only for good cause. That petition asks the court to approve the account, or to compel and approve one, to determine testacy and heirs, and to adjudicate final settlement and distribution, and the resulting order is conclusive on everyone given notice, subject to appeal. ExecutorLedger's South Dakota closing statement covers the unsupervised route under SDCL 29A-3-1003 only.
- Confirm the creditor claims period has run (or that you've made a diligent search for creditors) and pay all valid claims and administration expenses; the required tax attestation is usually a non-issue since South Dakota no longer imposes its own inheritance or estate tax.
- Distribute the remaining estate assets to the heirs or devisees who are entitled to them.
- File a verified (sworn) closing statement with the circuit court under SDCL 29A-3-1003, but not before four months have passed since your appointment, attesting that claims, taxes, and distribution have been handled.
- Send a copy of the closing statement and a full accounting to every heir, devisee, and known creditor whose claim isn't paid or barred; the accounting itself can be skipped only if everyone entitled to a copy consents to that in writing.
- If anyone objects, assets remain contested, or the estate needs closer court involvement, petition the circuit court for formal proceedings (an order of complete settlement) instead of closing by sworn statement.
South Dakota has no separate probate or surrogate court; this all happens in the circuit court (SDCL 29A-1-201(8)). One year after the closing statement is filed, the personal representative's appointment automatically terminates if no other proceeding involving the personal representative is then pending (SDCL 29A-3-1003(b)).
Section 5 of 7.The Inventory and the account explained for a first-time personal representative
SDCL 29A-3-706 names no classification scheme for the inventory. SDCL 29A-1-201(38) defines property to include both real and personal property, with no carve-out, so real property sits on the same single list as everything else, at its full value, with its own subtotal shown as a subtotal of that list rather than a second schedule that could be counted twice. Any label ExecutorLedger prints beside an item is this product's own description, never a statutory category.
The encumbrance the statute asks for, the type and amount of any encumbrance that may exist with reference to any item, is its own datum. ExecutorLedger records no encumbrance data, so each item prints a ruled blank for it, with a note that the entry is the preparer's to make. It is never netted against the value, because the statute keeps a gross fair market value and the encumbrance as two separate things, not one combined net figure.
Employing an appraiser is optional under SDCL 29A-3-707, for any asset whose value may not be readily ascertainable, and different people may appraise different kinds of assets. Once an appraiser is used, the disclosure is mandatory: the appraiser's name and address has to appear on the inventory beside the item or items they appraised. ExecutorLedger records no appraiser data, so this prints as a ruled line with the statute's own rule stated beside it.
A supplementary inventory under SDCL 29A-3-708 covers property found after the original inventory, and a value or description in the original that turns out to be erroneous or misleading. It shows the date-of-death value of a newly found item, or the revised value or description, and the appraisers or other data relied on, if any. It has no deadline of its own. Whether it is filed with the court depends on whether the original was filed: if the original was filed, the supplementary inventory is filed too; if not, it goes by mail or delivery to everyone who was sent the original and to any other interested person who requests it.
South Dakota asks for two kinds of verification, and both belong. SDCL 29A-1-310 deems every document filed with the court under the probate code, including the closing statement, to already include an oath or affirmation that its representations are true so far as the person filing it knows or is informed, with penalties for perjury possibly following deliberate falsification. Because an inventory is usually never filed, that deemed oath rarely reaches it, so ExecutorLedger prints South Dakota's unsworn declaration, under SDCL 18-7-6, on both documents. Its words are fixed by statute: a declaration under penalty of perjury under the law of South Dakota that the foregoing is true and correct, signed on a stated day, month and year, at a stated city or other location and state, with a printed name and a signature. That place line is unusual. No notary jurat appears anywhere on either document.
SDCL 29A-3-1003 sets no shape at all for the account that goes with the closing statement. The charge-and-discharge presentation ExecutorLedger prints, the same shape Utah, Nebraska and Idaho use, is this product's own choice, and the printed page says so rather than attributing it to the statute.
Section 6 of 7.Where ExecutorLedger fits
Recording is free for as long as the estate takes: every receipt and disbursement with its date and description, distributions per beneficiary, and a balance that checks itself as you go. ExecutorLedger builds South Dakota-style documents from those records, an inventory in the statute's own single, undifferentiated list and a closing statement carrying all four of SDCL 29A-3-1003's recitals, ready to transcribe or attach when you furnish a copy to an interested person or send a statement and accounting to a distributee. Neither is a court form, and your attorney should review them before anything is signed or filed. Every document previews free with your real numbers, and $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate.
Section 7 of 7.Questions South Dakota executors ask
Is there a court form for South Dakota's inventory or closing statement?
No. South Dakota's Unified Judicial System publishes no form for a decedent's estate inventory, account or closing statement. The only Initial Inventory form on the court's own site, UJS-140, is a conservatorship and guardianship form under chapter 5 and has nothing to do with a decedent's estate. SDCL 29A-3-706 and 29A-3-1003 say what a personal representative's inventory and closing statement must contain, and that is the whole requirement.
When is the South Dakota inventory due, and do I have to file it?
Within six months after appointment, or nine months after the decedent's death, whichever is later (SDCL 29A-3-706). Furnishing a copy to anyone who asks is mandatory and has to happen promptly, by mail or delivery. Filing the original with the court is the personal representative's own option.
How does a South Dakota estate close?
By filing a verified closing statement under SDCL 29A-3-1003 no earlier than four months after the date of the original appointment of a general personal representative. The statement carries four recitals: that creditors' claims have been resolved or are barred, that death taxes are paid (South Dakota's death tax chapters were repealed by SL 2014, chapter 59, so this is satisfied at nil), that the estate has been fully administered and distributed, and that copies of the statement and a full accounting were sent to every heir, devisee and known unpaid creditor. A supervised estate instead uses the formal route under SDCL 29A-3-1001.
Can a South Dakota estate close without an accounting?
Yes. SDCL 29A-3-1003(c) lets the accounting be waived if the people entitled to a copy of it consent in writing. If everyone entitled agrees, the estate can close without producing one.
How is a South Dakota personal representative paid?
SDCL 29A-3-719 sets reasonable compensation on seven factors, and where compensation is not set by will or the estate is intestate, a commission schedule on personal property accounted for: 5 percent of the first $1,000, 4 percent of the next $1,000 to $5,000, and 2.5 percent above $5,000. Real property accounted for earns compensation fixed by the court instead of a percentage, while real estate sold in the probate proceedings counts as personal property for this purpose.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes South Dakota practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.