Texas Estate Accounting: An Executor's Guide
Most Texas estates run as independent administrations. No judge signs off, so the accounting is what the beneficiaries signing receipts have to rely on. Here is the document Texas expects, when its deadlines fall, and what an executor is paid.
Section 1 of 7.What a Texas estate accounting is
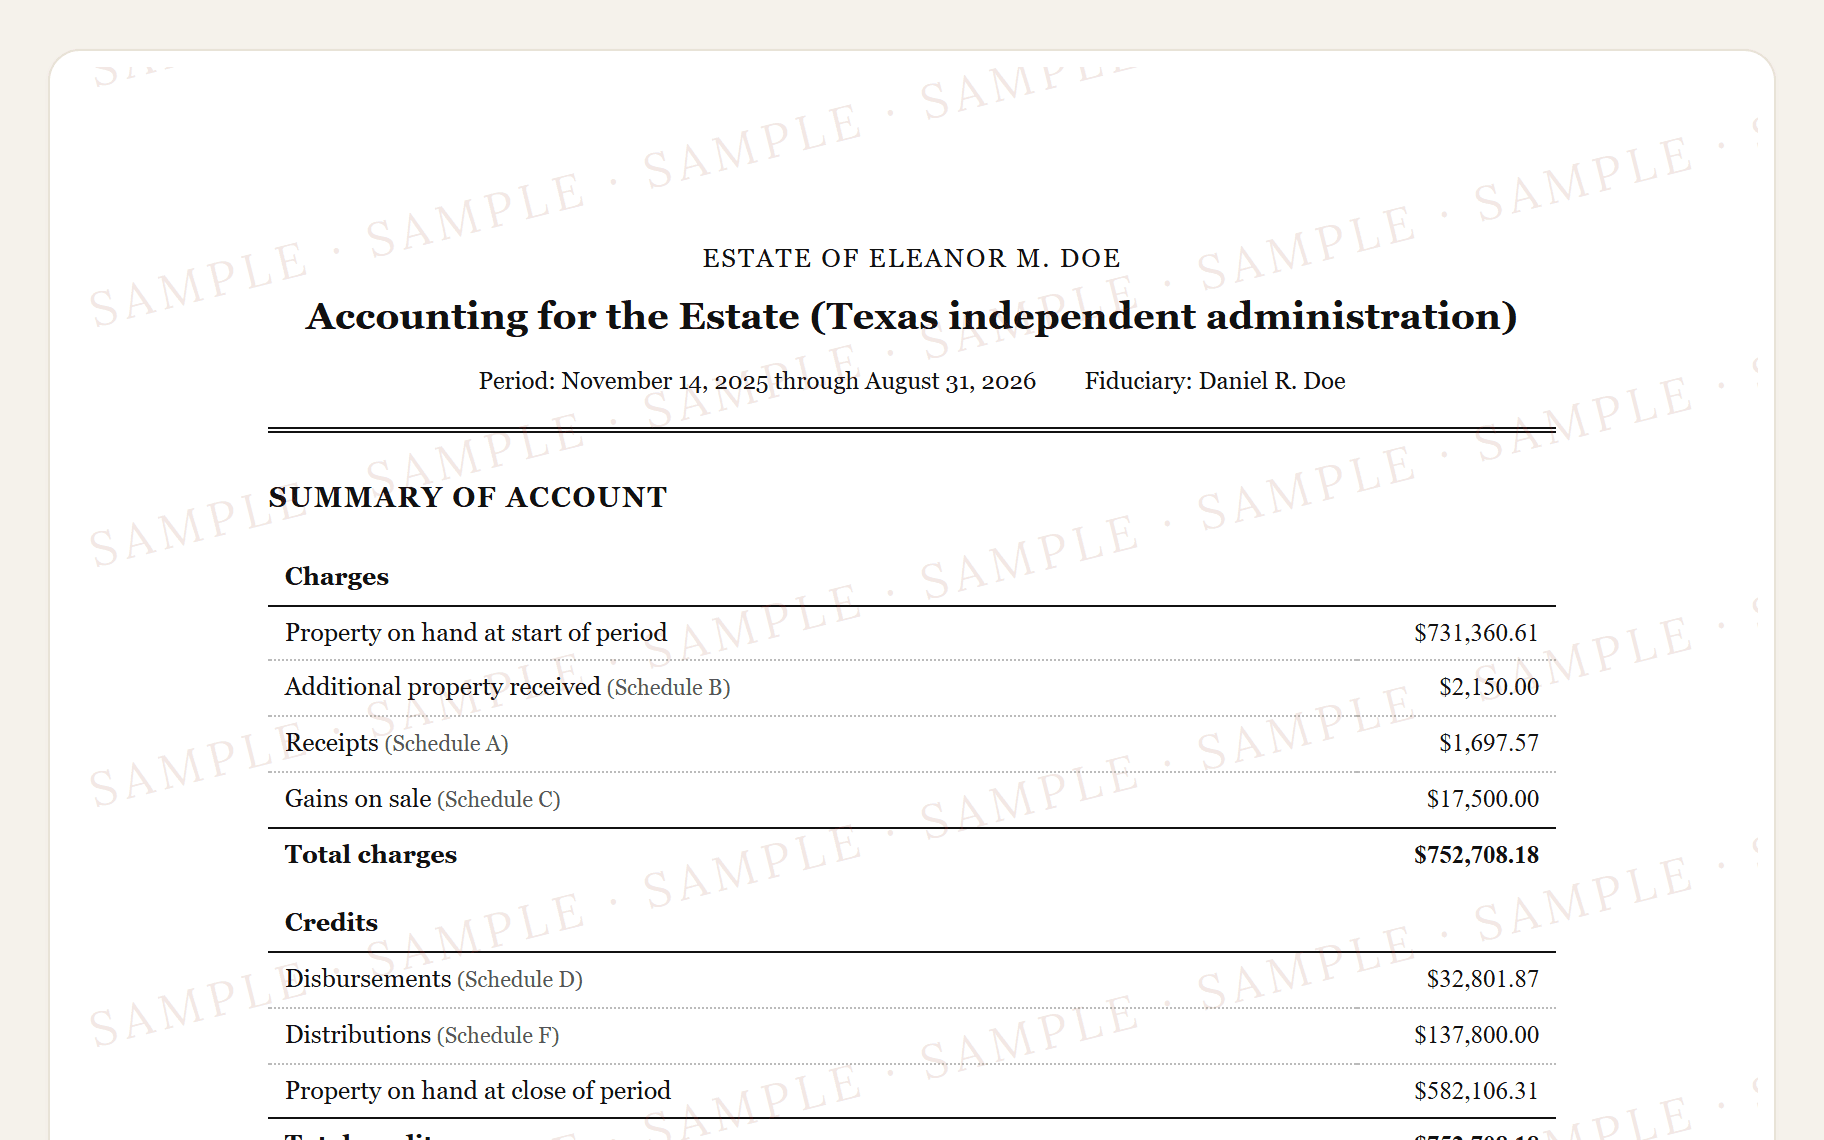
Every estate accounting is the same charge-and-discharge account: what you were answerable for on one side, what you did with it on the other, balancing to the penny. The mechanics are covered in How to prepare an estate accounting. What Texas adds is the shape. The document a Texas executor works toward is that account, carrying the figures a Tex. Est. Code §404.001 exhibit draws on. The sworn exhibit language is your attorney's to draft. The figures under it come from months of bank statements and receipts, and they are the same numbers whether anything is ever filed or not.
Because most Texas estates are independent administrations, no accounting lands on a court's desk on a routine schedule. The inventory or affidavit in lieu still does, within 90 days. That does not make the accounting optional. The beneficiaries you ask to sign receipts deserve a clear picture of where the money went.
Section 2 of 7.The Texas deadlines, and where each one comes from
- Day 30 (about 1 month)Publish notice to creditors in a local newspaper
Why
Under Tex. Est. Code §308.051, within 1 month after letters issue, publish notice to creditors in a newspaper in the county where letters were issued (or post/file if no newspaper); confirm the method and timing with your attorney. - Day 60 (about 2 months)Mail notice to known secured creditors
Why
Under Tex. Est. Code §308.053, within 2 months after letters issue, send certified-mail notice to each creditor with a secured claim (e.g. mortgage or car lien); confirm who must be noticed with your attorney. - Day 60 (about 2 months)Notify the beneficiaries named in the will
Why
Under Tex. Est. Code §308.002, certified-mail notice to will beneficiaries is typically due within 60 days after the order admitting the will to probate, which can come before letters issue, with an affidavit or certificate of compliance filed by day 90 under §308.004; this timeline anchors the notice to your letters date, so count from the order's date and confirm the exact dates with your attorney. - Day 90 (about 3 months)File the inventory or affidavit in lieu with the court
Why
Under Tex. Est. Code §309.051, the inventory, appraisement, and list of claims is typically due within 90 days after you qualify; many independent executors may instead file an affidavit in lieu (§309.056), and extensions are possible, so confirm with your attorney. - Day 425 (about 14 months)First annual account (dependent administrations only)
Why
Under Tex. Est. Code §359.001, in a court-supervised (dependent) administration, an annual account is due within 60 days after each anniversary of qualification; most Texas estates run independently and skip this, so confirm which type yours is with your attorney.
- Day 270 (about 9 months)Federal estate tax return, if one is required
Why
Under IRC §6075, IRS Form 706 is due 9 months after death, but only for estates over the federal exemption or electing portability (Texas has no state estate tax); ask your attorney or CPA whether it applies and about the 6-month extension.
Most Texas deadlines run from the day letters issue rather than from the date of death. Within 1 month after letters issue, publish notice to creditors in a newspaper in the county where letters were issued, or post or file it if there is no newspaper (Tex. Est. Code §308.051). Within 2 months after letters issue, send certified-mail notice to each creditor holding a secured claim, such as a mortgage or a car lien (§308.053). Confirm the method, timing, and who must be noticed with your attorney.
Read the full explanation
Notice to the people named in the will runs separately. Certified-mail notice to will beneficiaries is typically due within 60 days after the order admitting the will to probate, which can come before letters issue, with an affidavit or certificate of compliance filed by day 90 under §308.004 (§308.002). Confirm the exact dates with your attorney.
The inventory, appraisement, and list of claims is typically due within 90 days after you qualify (§309.051). Many independent executors may instead file an affidavit in lieu under §309.056, and extensions are possible, so confirm which route your estate takes. Do the inventory work early either way. Date-of-death values are the accounting's opening balance, and they are miserable to reconstruct later.
Two more depend on the estate. IRS Form 706 is due 9 months after death under IRC §6075, but only for estates over the federal exemption or electing portability. Texas has no state estate tax. Ask your attorney or CPA whether a federal return applies at all, and about the 6-month extension. In a court-supervised (dependent) administration, an annual account is due within 60 days after each anniversary of qualification (§359.001). Most Texas estates run independently and skip it. Confirm which type yours is with your attorney.
Section 3 of 7.What a Texas executor gets paid
Texas pays a commission on the cash that moves through the estate rather than on its size. Under Estates Code chapter 352, the commission is 5% of qualifying cash received plus 5% of qualifying cash paid out, capped at 5% of the gross estate under administration.
The exclusions are what usually shrink the figure. Money already on hand or in the decedent's bank or brokerage accounts at death does not count. Neither does life insurance or cash paid to beneficiaries as their share of the estate. An estate whose value sat in accounts at death and passed straight to the family can produce a commission close to nothing. Whether anything beyond chapter 352's math is available in your situation is a question for the estate's attorney.
Section 4 of 7.How a Texas independent administration closes
Confirm every debt and tax is paid first, because an independent executor distributes without court approval. Then distribute and collect a signed receipt from each beneficiary. Nobody reviews the numbers before the money leaves, so those signed receipts matter.
After that you may file a closing report or notice of closing. It is often skipped, and whether your county expects one is worth asking your attorney.
- Confirm all debts and taxes are paid. The independent executor then distributes without court approval.
- Distribute to beneficiaries and collect signed receipts.
- Optionally file a closing report or notice of closing with the court. This step is often skipped, so ask your attorney whether your county expects one.
Section 5 of 7.What only you can supply
Software handles the bookkeeping half: every transaction with its date, payee, and category, the inventory valued as of the date of death, each sale carried against the value the item was held at, and a running check that the totals balance.
The rest is yours. The sworn §404.001 exhibit language comes from your attorney. The exhibit also lists any debts and expenses the estate still owes, and any facts showing why the administration should not be closed. The ledger tracks neither. The appraisement and the list of claims in the §309.051 filing are not bookkeeping. Mortgages and liens are not tracked in the ledger, so property prints at gross value and you reduce it when you transcribe. Sign with your full legal name rather than an email address. And whether your administration is independent or dependent is a call for the estate's attorney.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger is free to use while you record the estate: assets at date-of-death value, every receipt and disbursement, and distributions per beneficiary. The Texas document is a charge-and-discharge account carrying the figures a §404.001 exhibit draws on. It previews free with your real numbers, watermarked, so you see the whole thing first. An accounting-through date produces an interim account for any period. $149 (one-time payment) per estate lifts the watermark from every document. Usually less than one attorney hour, and typically reimbursable by the estate. None of these are court forms. They are court-style documents, ready to transcribe onto whatever your filing requires, and your attorney should read one before anybody signs.
Section 7 of 7.Questions Texas executors ask
Does a Texas independent executor have to file an annual account?
The annual account under Tex. Est. Code §359.001 belongs to court-supervised, dependent administrations, due within 60 days after each anniversary of qualification. Most Texas estates run independently and skip it. Confirm with your attorney which type yours is.
When is the Texas inventory due?
The inventory, appraisement, and list of claims is typically due within 90 days after you qualify (§309.051). Many independent executors may instead file an affidavit in lieu (§309.056), and extensions are possible. Confirm which applies with your attorney.
What is a Texas Estates Code 404.001 accounting?
It is a sworn exhibit, and the sworn language is your attorney's to draft. The figures it draws on are ordinary charge-and-discharge numbers: what you were answerable for, what was paid out or distributed, and what remains. It also lists any debts and expenses the estate still owes, which the ledger does not track. A beneficiary can demand one from the executor once fifteen months have passed since letters first issued (§404.001(a)). Whether your estate must give one, and when, is a question for the attorney.
How much does an executor get paid in Texas?
Estates Code chapter 352 sets 5% of qualifying cash received plus 5% of qualifying cash paid out, capped at 5% of the gross estate. Cash already on hand or in the decedent's accounts at death, life insurance, and cash paid to beneficiaries as their share of the estate are excluded, so the figure is often small. Whether anything beyond that math is available in your situation is a question for the estate's attorney.
Does a Texas executor file a closing report?
In an independent administration you may file a closing report or notice of closing, and it is often skipped. The distributions themselves need no court approval. Whether your county expects one is worth asking your attorney.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes Texas practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.