Pennsylvania Estate Accounting: An Executor's Guide
Most Pennsylvania estates settle without a judge reading the numbers, but the beneficiaries read them before they sign. Here is the shape a Pennsylvania estate account takes, when the dates fall, and what the family settlement route asks of you.
Section 1 of 7.The Pennsylvania model account: what the document is
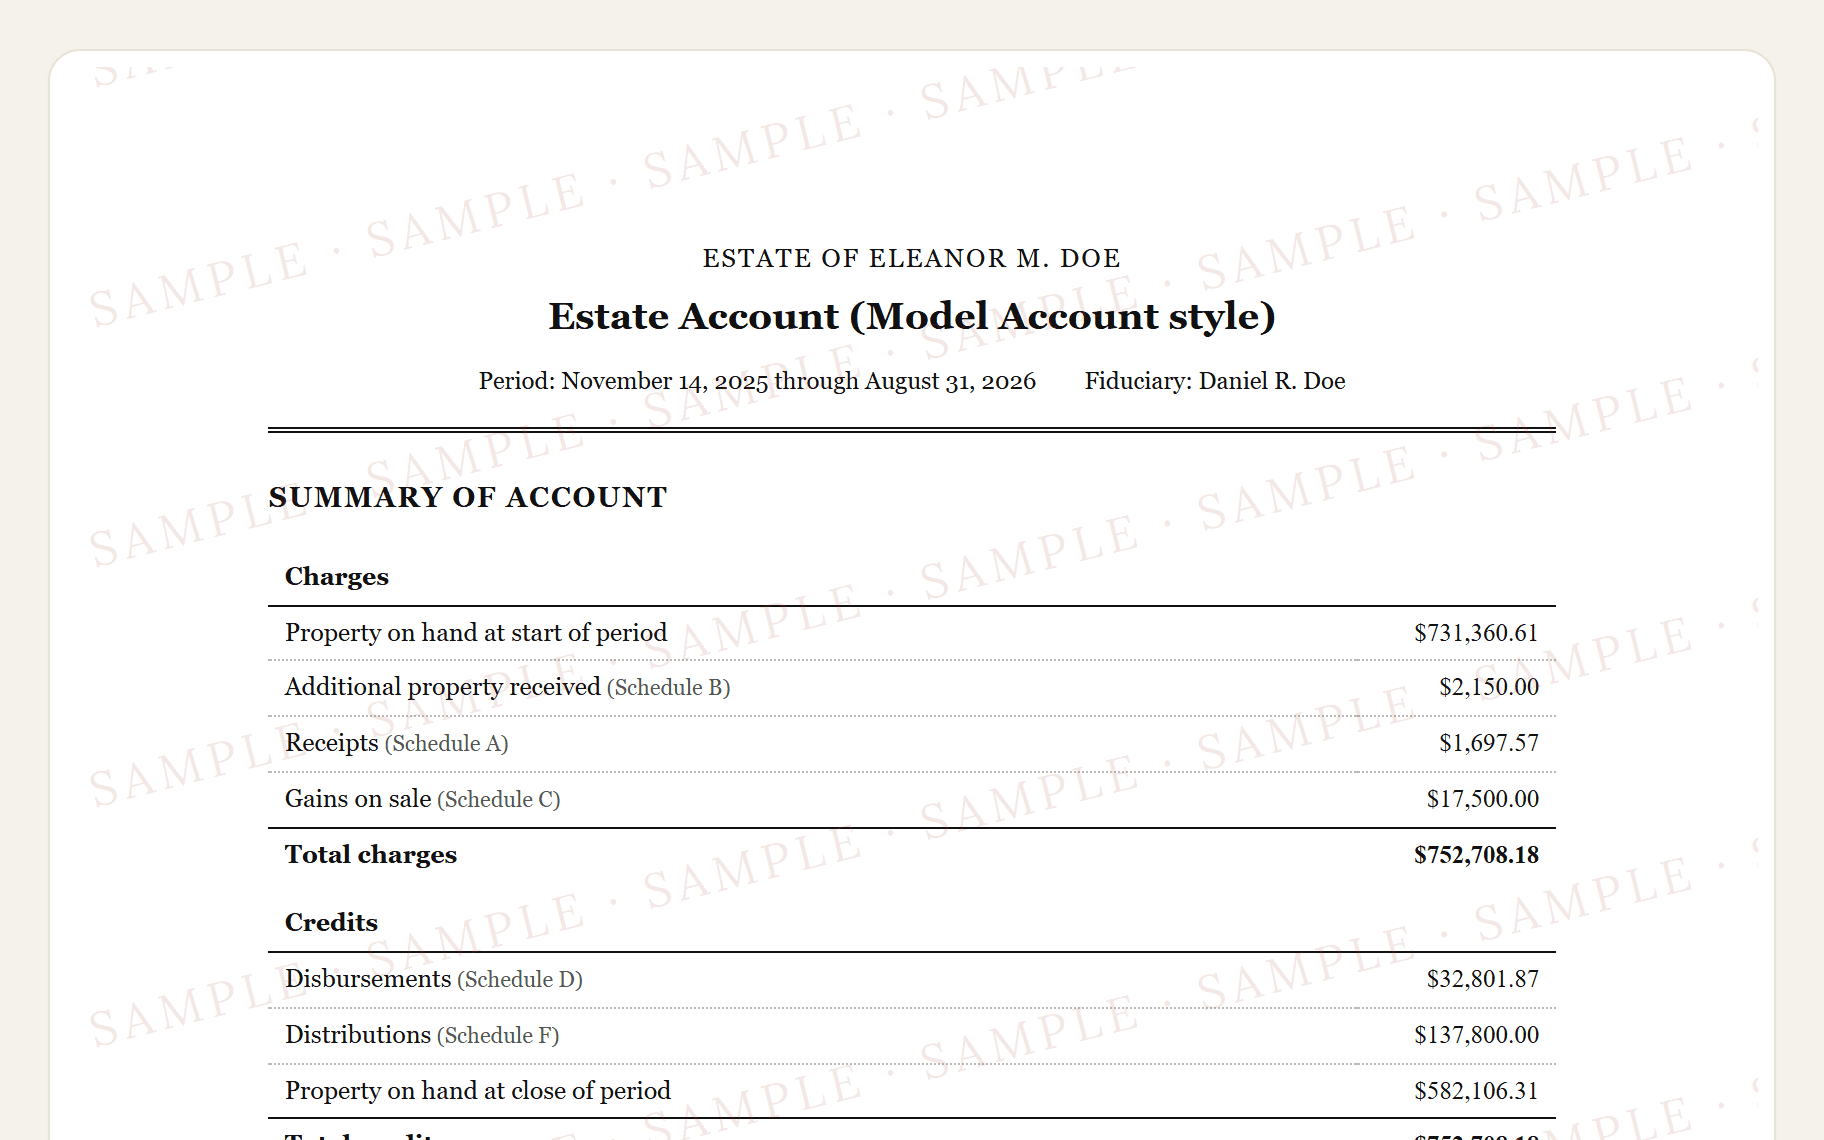
Pennsylvania practice expects the shape known as the model estate account. It is a charge-and-discharge account: one side lists everything you are answerable for, the other everything that left or remains, and the two totals have to equal each other to the penny. The charges side of the summary carries property on hand at the start of the period, additional property received, receipts, and gains on sale. The credits side carries disbursements, losses on sale, distributions, and property on hand at the close.
Behind that summary sit the itemized schedules: receipts, additional property received, gains, disbursements, losses, and distributions, plus a per-beneficiary rollup. That rollup is what a beneficiary looks for before signing anything. Pa. Orphans' Court Rule 2.1 calls for principal and income to be accounted for separately, so each itemized schedule shows the estate's own money and its earnings in separate columns. Every sale prints both numbers, what the item sold for and what it was carried at, so a reviewer can check the arithmetic from the document alone.
ExecutorLedger exports this as an Estate Account in the model account style, with your real figures, ready to transcribe or to hand to the estate's attorney. It is court-style, not a court form, and formats drift. The estate's attorney reading it is the step that makes anything filing-ready.
Section 2 of 7.The Pennsylvania dates that bind
- Day 14 (about 2 weeks)Advertise the grant of letters in two newspapers
Why
20 Pa. C.S. §3162 requires advertising the grant of letters immediately after issuance, once a week for three weeks in a general-circulation newspaper and the county legal journal. There is no fixed day count, so start promptly and confirm the details with your attorney. - Day 90 (about 3 months)Send notice to beneficiaries and heirs
Why
Under Pa. Orphans' Court Rule 10.5, written notice of estate administration is due to beneficiaries and intestate heirs within 3 months after letters, with a certification of notice filed with the Register within 10 days after giving it; confirm the recipient list with your attorney. - Day 180 (about 6 months)Spousal elective share window closes 6 months after probate
Why
20 Pa. C.S. §2210(b) lets a surviving spouse elect to take a one-third elective share under §2203 by filing a signed writing with the clerk of the orphans' court within six months after the decedent's death or six months after the date of probate, whichever is later; the probate clock is the later one, and Pennsylvania letters issue when the Register of Wills admits the will, so this timeline runs from your letters date (approximated here as 180 days). The court can extend the time only on an application the spouse files within that window, a missed filing is deemed a waiver, and the right does not arise in some pending-divorce situations (20 Pa. C.S. §2203(c)); distributing before this window closes risks having to recover property if an election is filed, so confirm with your attorney whether an election is possible in this estate.
- Day 270 (about 9 months)File the PA inheritance tax return
Why
Under 72 P.S. §9136, the Pennsylvania inheritance tax return is typically due 9 months after death, and paying the tax within 3 months of death earns a 5% discount under §9142; confirm timing and any extension with your attorney. - Day 270 (about 9 months)File the inventory with the Register of Wills
Why
Under 20 Pa. C.S. §3301(c), the inventory is due no later than the inheritance tax return due date (typically 9 months after death) or when the account is filed, whichever is earlier, and can be demanded sooner; confirm your date with your attorney. - Day 270 (about 9 months)Federal estate tax return, if one is required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax; confirm applicability and timing with your attorney. - Day 730 (about 2 years)File a status report if the estate is still open
Why
Under Pa. Orphans' Court Rule 10.6, if administration is not complete within 2 years of death, a status report is due to the Register of Wills then and annually until the estate closes; confirm the form and timing with your attorney.
Advertising comes first. 20 Pa.C.S. §3162 requires advertising the grant of letters immediately after issuance, once a week for three weeks, in a general-circulation newspaper and the county legal journal. There is no fixed day count, so start promptly and confirm the details with your attorney.
Read the full explanation
Notice comes next. Pa. Orphans' Court Rule 10.5 requires written notice of estate administration to beneficiaries and intestate heirs within 3 months after letters, with a certification of notice filed with the Register within 10 days after you give it. Who belongs on the recipient list is a judgment call, so confirm it with your attorney.
The inventory and the tax return travel together. Under 20 Pa.C.S. §3301(c) the inventory is due to the Register of Wills no later than the inheritance tax return due date, typically 9 months after death, or when the account is filed, whichever is earlier. It can also be demanded sooner. The Pennsylvania inheritance tax return is itself typically due 9 months after death under 72 P.S. §9136, and paying the tax within 3 months of death earns a 5% discount under §9142. That discount date comes long before the estate feels finished, so plan for it. Confirm the timing and any extension with your attorney.
A federal estate tax return is due 9 months after death under IRC §6075, with a 6-month extension available, but only if the gross estate exceeds the federal exemption or the estate elects portability. Ask your attorney whether one is required. If administration is not complete within 2 years of death, Pa. Orphans' Court Rule 10.6 calls for a status report to the Register of Wills at that point, and annually until the estate closes. Confirm the form and timing with your attorney.
Section 3 of 7.Family settlement agreement, or a formal PA Orphans' Court accounting
Most Pennsylvania estates close this way. You prepare the account and a proposed schedule of distribution. Every interested party signs a Family Settlement Agreement, which is the common, informal route. You make final distributions and collect receipts. Then you file the status report that closes the estate's register entry.
If anyone won't sign, the account is filed formally with the Orphans' Court instead. You don't have to choose in advance, because the account is built from the same ledger either way. The informal route only works if every interested party signs, and the account is what they read before deciding.
- Prepare the account and a proposed schedule of distribution.
- Have every interested party sign a Family Settlement Agreement, the common and informal route. If anyone won't, file a formal account with the Orphans' Court instead.
- Make final distributions and collect receipts.
- File the status report closing the estate register entry.
Section 4 of 7.What a Pennsylvania executor gets paid
Pennsylvania has no fee schedule. 20 Pa.C.S. §3537 promises only compensation that is 'reasonable and just.' In practice many Pennsylvania courts use the Johnson Estate guideline as a benchmark: 5% of the first $100,000, 4% of $100,000 to $200,000, 3% of $200,000 to $1,000,000, 2% of $1,000,000 to $2,000,000, 1.5% of $2,000,000 to $3,000,000, 1% of $3,000,000 to $4,000,000, and 0.5% of $4,000,000 to $5,000,000.
The guideline is a benchmark rather than a rule, and it is silent above $5,000,000. That portion is for the court to judge as reasonable. Section 3537's standard is still 'reasonable and just,' so keep dated records of what you did as well as what you spent, and raise the fee with the estate's attorney before you take one.
Section 5 of 7.What software prepares, and what only you can supply
Software can do the bookkeeping: hold every receipt, disbursement, sale, and distribution, keep the two sides balanced as you go, and print the account and the inventory whenever you need them, including an interim account run through any date you pick.
It can't read the will or the deed. The ledger tracks no mortgages or liens, so values print gross and an encumbered property needs adjusting when you transcribe. Whether an asset belongs on a Pennsylvania inventory at all, including survivorship property and beneficiary-designated accounts, is a question for the estate's attorney. So is the proposed schedule of distribution, because the shares come from the will rather than the ledger. The caption is yours, and the account should be signed with your full legal name.
One trap catches people early. If the inventory lists the money in the decedent's bank account at death, and the ledger records that same money again when it arrives to fund the estate account, the accounting counts it twice and overstates the estate.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger is free to record in for as long as the estate takes. Every document, including the Pennsylvania Estate Account in the model account style and the inventory, opens as a watermarked preview with your real numbers, nothing blurred or withheld. $149 (one-time payment) lifts the watermark from all of them, with as many exports as you need, forever. Usually less than one attorney hour, and typically reimbursable by the estate.
Section 7 of 7.Questions Pennsylvania executors ask
Do I have to file an accounting with the PA Orphans' Court?
Most Pennsylvania estates don't. The common route is a Family Settlement Agreement signed by every interested party, after you prepare the account and a proposed schedule of distribution. If someone won't sign, a formal account goes to the Orphans' Court instead. Which path your estate is on is a question for its attorney.
When is the Pennsylvania inventory due?
20 Pa.C.S. §3301(c) puts the inventory with the Register of Wills no later than the inheritance tax return due date, typically 9 months after death, or when the account is filed, whichever is earlier. It can also be demanded sooner. Confirm your date with your attorney.
Is there a Pennsylvania estate accounting template?
Pennsylvania practice expects the model estate account shape. ExecutorLedger builds a court-style Estate Account (Model Account style) in that shape from your ledger, ready to transcribe or hand to the attorney. It is not a court form and doesn't replace their review.
How much is a Pennsylvania executor paid?
20 Pa.C.S. §3537 says only that compensation must be 'reasonable and just.' Many Pennsylvania courts use the Johnson Estate guideline as a benchmark, from 5% of the first $100,000 down to 0.5% of $4,000,000 to $5,000,000, and it is silent above $5,000,000. Judges are not bound by the guideline, so raise the fee with the estate's attorney before you take one.
The estate has been open more than two years. What happens now?
Pa. Orphans' Court Rule 10.6 calls for a status report to the Register of Wills if administration is not complete within 2 years of death, and annually after that until the estate closes. Confirm the form and timing with your attorney.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes Pennsylvania practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.