New York Estate Accounting: An Executor's Guide
New York calls the filed version a judicial accounting, and most estates close without one. This page covers both: the JA-7 schedules the Surrogate's Court expects, and the receipt-and-release route most New York estates take.
Section 1 of 7.The document New York expects: the JA-7 schedules
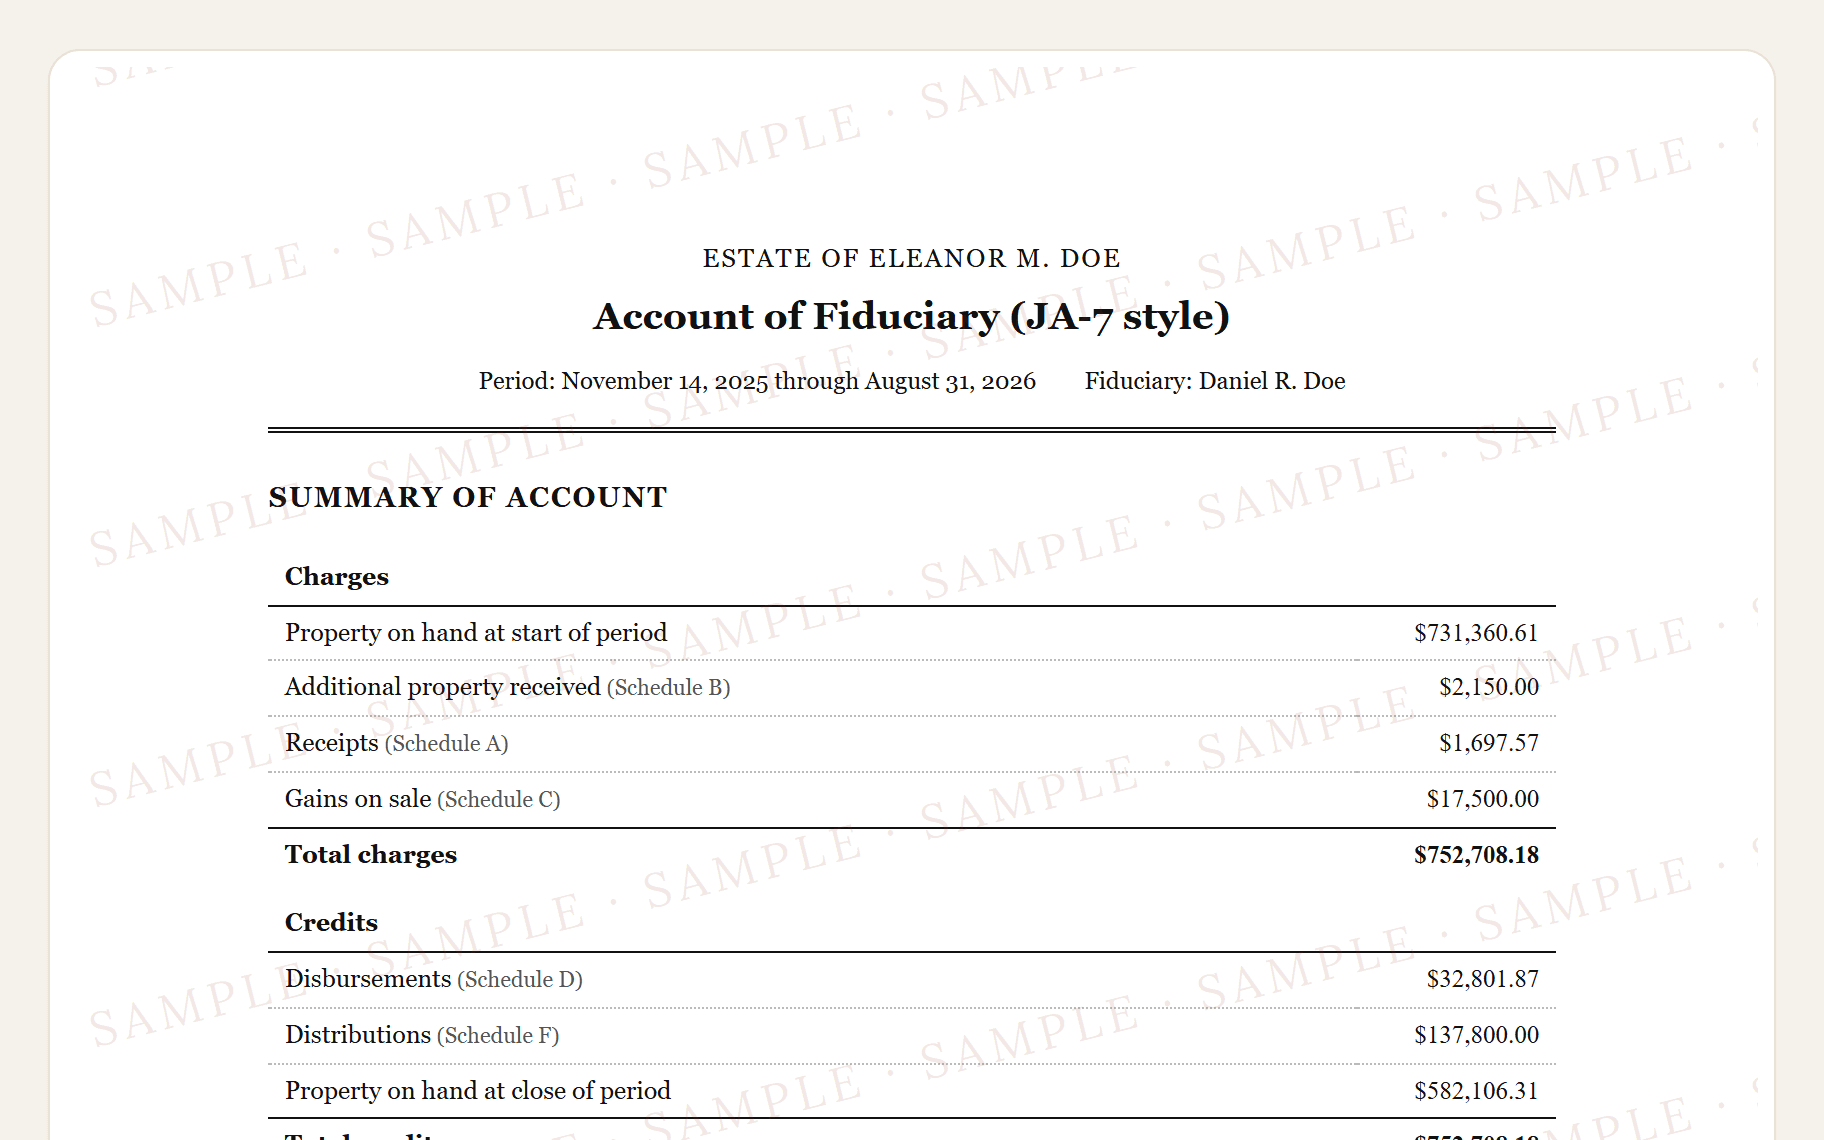
A New York accounting is a set of schedules rather than a single page. Practitioners know the shape as the JA-7 schedules. Underneath, it is the same structure every state uses: everything you were answerable for on one side, everything that left or remains on the other, and the two sides equal to the penny. The schedules itemize receipts, disbursements, gains and losses on sales, distributions, and the property still on hand.
New York's format also keeps the estate's own money and the money it earned while open in separate columns. Principal is the property that existed at death and what you collected of it. Income is what that property produced afterward: interest, dividends, rent. That split is close to impossible to reconstruct a year later from bank statements, so tag each entry as principal or income the day you record it.
ExecutorLedger's version is titled Account of Fiduciary (JA-7 style). It is not a court form, and you don't file it as it prints. You get a complete, balanced document with your real numbers in it, ready for your attorney to read and for you to transcribe into the account your Surrogate's Court expects.
Section 2 of 7.The dates a New York executor works against
- Day 180 (about 6 months)Spousal right of election window closes 6 months after letters
Why
Under EPTL §5-1.1-A, a surviving spouse may elect to take an elective share of the estate (one third of the net estate or $50,000, whichever is greater, never more than the whole estate) by serving notice on the personal representative and filing it in the Surrogate's Court within 6 months after letters issue (approximated here as 180 days), and in no event later than 2 years after death; the court can extend that time or relieve a spouse from a late filing, so distributing before this window closes risks having to recover property if an election is filed; confirm with your attorney whether an election is possible in this estate. - Day 210 (about 7 months)Creditor claim period ends (7-month mark)
Why
Under SCPA §1802, creditors generally have 7 months from letters to present claims (approximated here as 210 days, two to five days short of the full 7 months), and distributing earlier can expose you personally, so confirm timing with your attorney before paying anyone out. - Day 270 (about 9 months)File the inventory of assets with the court
Why
Under 22 NYCRR §207.20, the Inventory of Assets form is typically due within 9 months after letters issue (late filing can affect commissions); confirm the exact date with your attorney. - Day 730 (about 2 years)Report to the court if the estate is still open
Why
Under 22 NYCRR §207.42, a report of estate not fully distributed is typically due 2 years after letters (3 years if a federal estate tax return is required); confirm with your attorney.
- Day 270 (about 9 months)Federal estate tax return due, if one is required
Why
Under IRC §6075 (Form 706), this is due 9 months after death only if the gross estate exceeds the federal exemption or the estate elects portability, and extensions are common; confirm whether a return is needed with your attorney. - Day 270 (about 9 months)New York estate tax return due, if one is required
Why
Under N.Y. Tax Law §972 (Form ET-706), this is due 9 months after death only if the estate exceeds New York's basic exclusion amount; confirm whether filing is required with your attorney.
Several clocks start when letters issue. The Inventory of Assets form is typically due within 9 months after letters issue (22 NYCRR §207.20). Late filing can affect commissions, so confirm the exact date with your attorney. Separately, creditors generally have 7 months from letters to present claims (SCPA §1802). Distributing earlier can expose you personally, so confirm the timing with your attorney before paying anyone out.
Read the full explanation
Two tax returns may or may not apply. A federal estate tax return, Form 706, is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability (IRC §6075). Extensions are common, and whether one is needed is a question for your attorney. A New York estate tax return, Form ET-706, is due 9 months after death, but only if the estate exceeds New York's basic exclusion amount (N.Y. Tax Law §972). Ask your attorney whether a filing is required.
One date sits further out. If the estate is still open 2 years after letters, or 3 years if a federal estate tax return is required, a report of estate not fully distributed is typically due (22 NYCRR §207.42). Estates often run that long for ordinary reasons, so confirm the date with your attorney.
Section 3 of 7.What a New York executor is paid
New York sets commissions by statute, SCPA §2307, and the arithmetic surprises people. The full schedule runs 5% of the first $100,000, 4% of $100,000 to $300,000, 3% of $300,000 to $1,000,000, 2.5% of $1,000,000 to $5,000,000, and 2% of everything above $5,000,000. You do not apply that once to the estate's value. You take half the schedule on the sums you received, and half the schedule on the sums you paid out. Gross rents collected earn a separate 5%.
Sums received and sums paid out are two different running totals, and neither is the inventory figure. Any figure a calculator gives you is an estimate. Confirm it with the estate's attorney before you take anything.
Section 4 of 7.How New York estates usually close
Most close without a judge ever reading the numbers. You share the accounting with every beneficiary, collect a signed receipt and release from each of them, then make the final distributions and close the estate account. That is the informal route. Informal only means nothing is filed. A beneficiary who signs a release is giving up their claim, so the accounting behind it needs to be complete.
If anyone won't sign, you petition the Surrogate's Court for judicial settlement of the account instead, and the schedules get read by people looking for holes. You can't know in advance which route you'll end up on, so keep the books to the filed standard from the first week. Both documents come out of the same records.
- Share the accounting with every beneficiary.
- Collect a signed receipt and release from each beneficiary (the informal route).
- If anyone won't sign, petition the Surrogate's Court for judicial settlement of the account instead.
- Make final distributions and close the estate account.
Section 5 of 7.What software can prepare, and what only you can supply
Software can do the bookkeeping: every receipt and disbursement with its date, payee, and category, principal and income tagged apart, both numbers on a sale (the proceeds and the value the asset was inventoried at), and a running check that charges equal credits. It can lay that out in the JA-7 schedule shape and in the plainer informal accounting, from the same figures.
It cannot supply the caption: the county, the file number, your fiduciary title. It cannot read the will, so what the will requires of you is a question for the attorney. It doesn't track mortgages or liens, so values print gross and you adjust them when you transcribe. And it cannot judge whether it is safe to distribute once the 7-month creditor window has run, or whether your estate is headed for a judicial settlement. Those are legal calls.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger is free while you work, for as long as the estate takes. Every court-style New York document previews free with your real numbers, watermarked and complete: the Account of Fiduciary in the JA-7 schedule style, the inventory report, and the informal accounting with its per-beneficiary distribution statements. $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate. These are court-style documents shaped for transcription, not court forms, and your attorney should read them before anyone signs.
Section 7 of 7.Questions New York executors ask
Do I have to file a New York judicial accounting with the Surrogate's Court?
Usually not. Most New York estates close informally: you share the accounting with every beneficiary, collect a signed receipt and release from each one, then make final distributions and close the estate account. If someone won't sign, you petition the Surrogate's Court for judicial settlement of the account instead. Which route your estate takes is a question for its attorney.
What are the JA-7 schedules?
JA-7 is what New York practice calls the schedule set behind a fiduciary's judicial accounting. A summary that has to balance sits on top, and the schedules under it cover receipts, disbursements, gains and losses, distributions, and the property still on hand, with the estate's own money and the income it earned in separate columns. ExecutorLedger exports a court-style document in that shape from your ledger, ready to transcribe into the account the court expects.
When is the New York inventory of assets due?
The Inventory of Assets form is typically due within 9 months after letters issue, under 22 NYCRR §207.20. Late filing can affect your commissions. Confirm the exact date with your attorney.
How much does a New York executor get paid?
SCPA §2307 sets a schedule of 5% of the first $100,000, 4% of $100,000 to $300,000, 3% of $300,000 to $1,000,000, 2.5% of $1,000,000 to $5,000,000, and 2% above $5,000,000. You take half of that schedule on the sums received and half on the sums paid out, plus 5% of gross rents collected. Any figure you compute is an estimate to confirm with the estate's attorney.
Can I distribute to beneficiaries before the seven months are up?
Creditors generally have 7 months from letters to present claims under SCPA §1802. Distributing earlier can expose you personally, so confirm the timing with your attorney before paying anyone out. When beneficiaries ask why the money is sitting there, the 7-month claim window is the answer.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes New York practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.