Maryland Estate Accounting: An Executor's Guide
A Maryland estate accounting is generally two filings: an inventory within three months of your appointment, and an administration account within nine. If you elected modified administration, a single final report replaces both. Here is what each contains, when it is due, and how a Maryland estate closes.
Section 1 of 7.The Maryland inventory forms: RW1122 and RW1123
Maryland probate runs through the county Register of Wills, under the Orphans' Court. The inventory comes first: Form RW1122, the Inventory Summary, and Form RW1123, the Supporting Schedule (Md. Rule 6-402; Md. Code, Est. & Trusts §7-201). The summary has seven lettered rows and a Total: A Real, B Leasehold, C Tangible personal, D Corporate stocks, E Bonds, notes, mortgages, debts due to the decedent, F Bank accounts, savings and loan accounts, cash, and G All other interests. Each letter equals the footed total of its own RW1123 page.
You list what the decedent owned at death, solely or as a tenant in common, at gross fair market value as of that day, with any mortgage or lien disclosed in the description rather than netted out. Est. & Trusts §7-202 lets you value some things yourself: exchange-listed and over-the-counter stock, debts owed to the decedent including bonds and notes, and bank accounts and cash. Real and leasehold property can instead be carried at the full cash value for property-tax assessment as of the most recent date of finality, or at the contract price of an arm's-length sale settling within a year of death (§7-202(c)); a vehicle can be valued from a used-car guide (§7-202(d)). Anything else, such as household contents or a business interest, needs an independent appraisal (§7-202(a)(3)). Confirm with the estate's attorney which method fits an item.
Property that passes outside probate goes on the Information Report (Form RW1124, Md. Rule 6-404) instead, though an IRA, annuity, or life insurance payable to the estate, or with no named beneficiary, is a probate asset on Schedule G. The rest of the sorting is yours: bonds, notes, and debts owed to the decedent on E; directly held stock certificates on D; leasehold property (land subject to a ground rent the decedent didn't own) on B. Real property outside Maryland stays off the inventory entirely and goes on the Information Report instead. Brokerage accounts stay on G, per register practice, even when they hold stocks and bonds.
Section 2 of 7.The deadlines, and the citations behind them
- Day 20 (about 3 weeks)List of interested persons (heirs and legatees)
Why
Under Md. Rule 6-316, within 20 days after appointment under administrative probate the personal representative generally must file a list of interested persons (heirs and legatees, Form RW1104) with the Register of Wills so everyone entitled to notice of the appointment is identified; confirm who must be listed and the exact due date with your attorney. - Day 90 (about 3 months)Inventory due to Register of Wills
Why
Under Md. Code, Est. & Trusts §7-201 and Md. Rule 6-402, the personal representative generally must file an inventory of the probate assets, valued as of the date of death, within 3 months after appointment (Forms RW1122/RW1123); confirm the exact due date and any appraisal requirements with your attorney. - Day 90 (about 3 months)Information Report on non-probate property (inheritance tax)
Why
Under Md. Code, Tax-Gen. §7-224 and Md. Rule 6-404, an Information Report (Form RW1124) disclosing non-probate property such as joint accounts, trusts, beneficiary-designated assets, and certain pre-death transfers is generally due within 3 months after appointment so the register can determine inheritance tax; confirm what must be reported and the exact due date with your attorney. - Day 90 (about 3 months)Last day to elect modified administration
Why
Under Md. Code, Est. & Trusts §5-702, an eligible estate (typically one where all residuary takers are the personal representative, inheritance-tax-exempt family members, or exempt trusts, and all of them consent) may elect streamlined modified administration only within 3 months after appointment, which replaces the inventory and accounts with a 10-month final report; confirm eligibility and whether electing makes sense with your attorney. - Day 270 (about 9 months)Spousal elective share window closes by 9 months after appointment
Why
Md. Code, Est. & Trusts §3-407 lets a surviving spouse elect to take an elective share of the estate subject to election (one third of its value if there is surviving issue, one half if not, reduced by spousal benefits, under §3-403) within the later of 9 months after the date of death or 6 months after the first appointment of a personal representative; because this timeline supports one clock, the date shown is calendared conservatively at 9 months after your appointment (approximated here as 270 days), which is never earlier than either statutory clock, and for good cause the court can extend the election period 3 months at a time; distributing before the window closes risks having to recover property if an election is filed; confirm the operative date and whether an election is possible in this estate with your attorney. - Day 270 (about 9 months)First administration account due
Why
Under Md. Code, Est. & Trusts §7-305, the first administration account is generally due within 9 months after appointment, and under Md. Rule 6-417(a) each later account is generally due 6 months after the prior account's approval or 9 months after its filing, whichever comes first, until the final account is approved; confirm the exact due date and any extension with your attorney.
- Day 180 (about 6 months)Creditor claims bar date
Why
Under Md. Code, Est. & Trusts §8-103, creditor claims are generally barred unless presented within 6 months after the date of death, and mailing a creditor written notice can cut that creditor's window to 2 months after mailing, so calendar this bar date before paying claims or distributing; confirm the operative bar date for each creditor with your attorney. - Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax; confirm applicability and timing with your attorney.
Within 20 days after appointment under administrative probate, you generally file the list of interested persons, the heirs and legatees, on Form RW1104 (Md. Rule 6-316). Two more filings are generally due within 3 months after appointment: the inventory, valued as of the date of death (Est. & Trusts §7-201; Md. Rule 6-402), and the Information Report on non-probate property, which lets the register determine inheritance tax (Tax-Gen. §7-224; Md. Rule 6-404).
Read the full explanation
Creditor claims are generally barred unless presented within 6 months after the date of death (Est. & Trusts §8-103), and written notice mailed to a creditor can cut that creditor's window to 2 months after mailing. The first administration account is generally due within 9 months after appointment (Est. & Trusts §7-305). Until the final account is approved, each later account is generally due at whichever comes first: 6 months after the prior account's approval or 9 months after its filing (Md. Rule 6-417(a)). Confirm each date, and any extension, with the estate's attorney.
Section 3 of 7.Inside a Maryland administration account (Md. Rule 6-417)
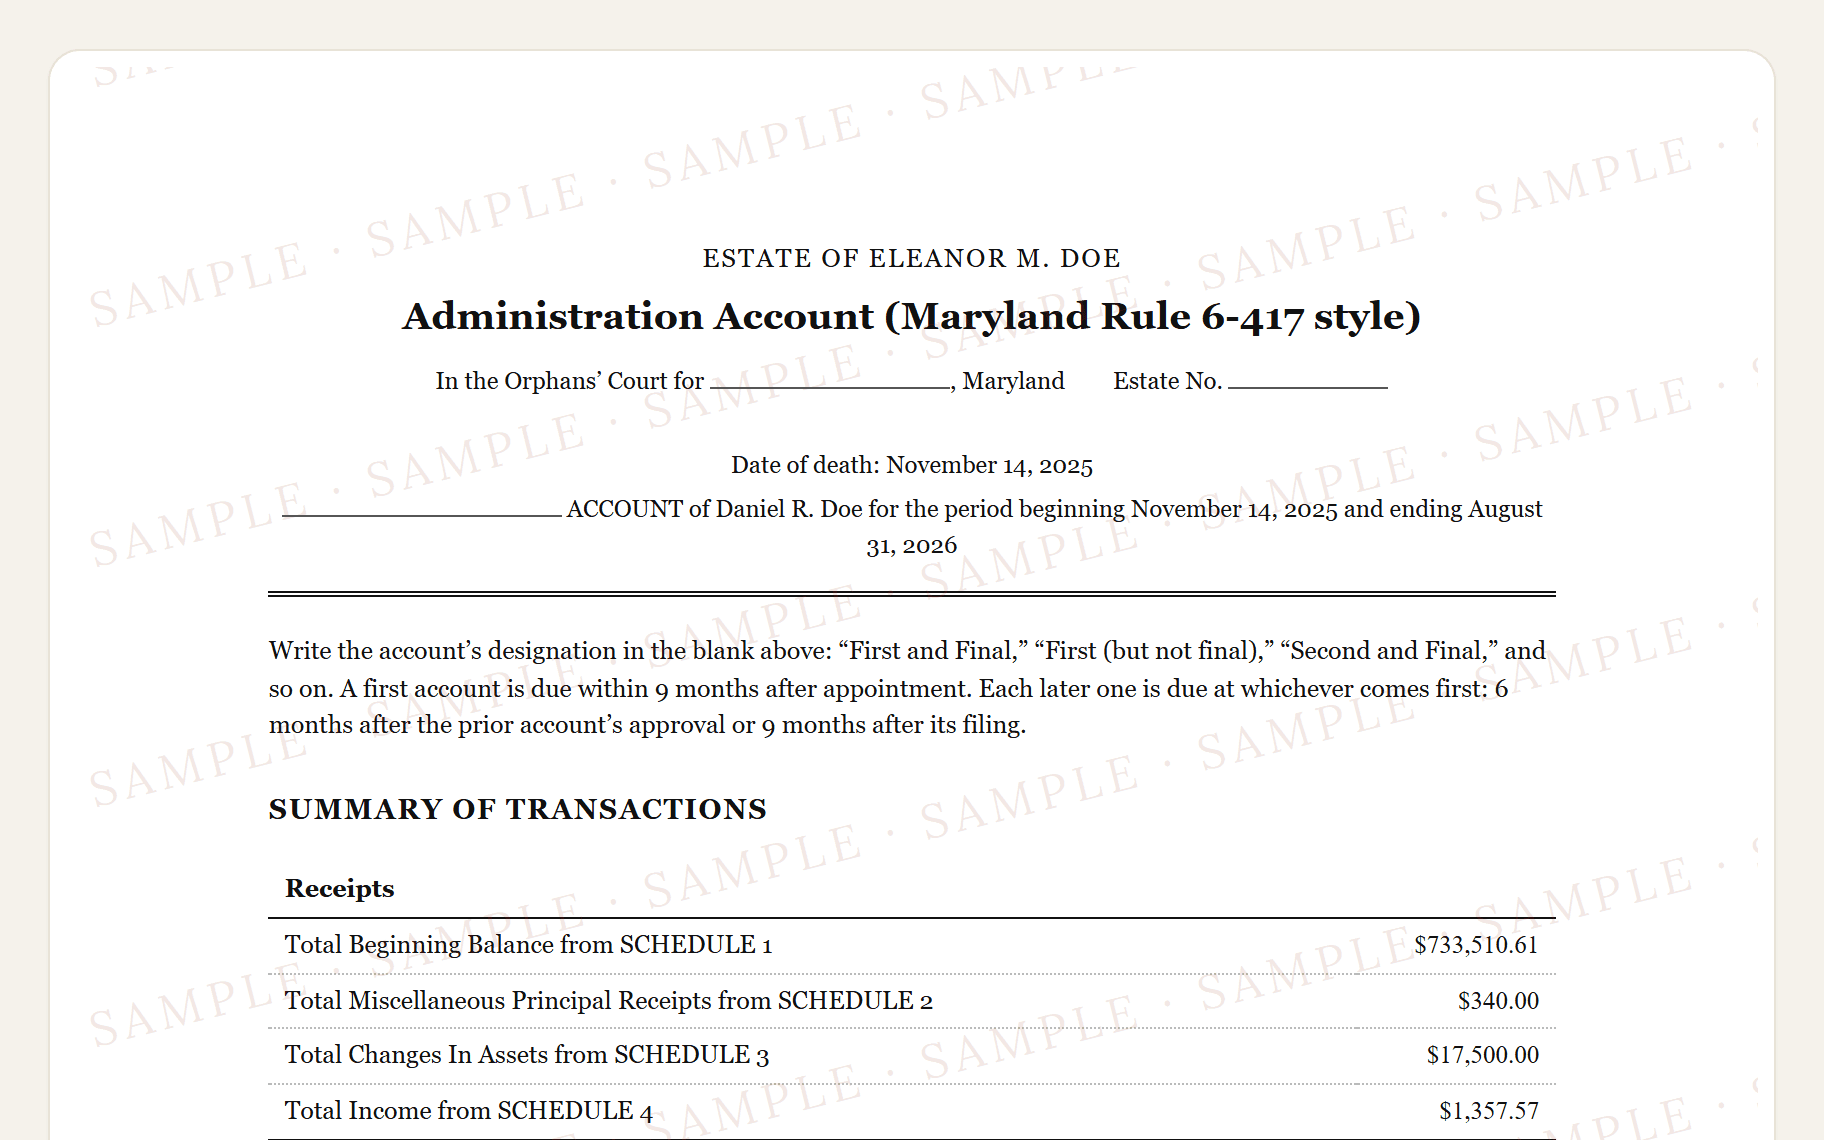
There is no official court form for the account. The Judiciary's tip sheet says so, and the Registers of Wills publish a sample guide instead. Its suggested format is not required, but the information and documentation it describes are.
Page one is the Summary of Transactions, a receipts column totaling Schedules 1 through 4 against a disbursements column totaling Schedules 5 through 7, and the two must be equal. Schedule 1 is the beginning balance, the assets per inventory in the same A through G categories; Schedule 2, miscellaneous principal receipts; Schedule 3, changes in assets including gains and losses, measured against inventory value; Schedule 4, income earned since the date of death; Schedule 5, disbursements; Schedule 6, distribution and inheritance tax. Schedule 7, only in an interim account, needs a written explanation of why the estate stays open.
The split between principal and income matters here, because inheritance tax falls on principal only. Taxable principal is Schedules 1 and 2 less Schedule 5, while Schedules 3 and 4 are exempt (Tax-Gen. §7-203(j)). Each Schedule 6 line carries a tax status, generally 10% withheld and paid to the Register of Wills from a non-exempt taker's bequest, or 11.11111% where the will's tax clause shifts the tax to the residue. Section 7-203's exempt list runs wider than close relatives. It also covers 501(c)(3) charities, the family allowance, anyone taking $1,000 or less in total, post-death income and gains, and, for recent dates of death, a registered domestic partner. Which version of the list applies turns on the date of death, so confirm each taker's status with the estate's attorney.
The rest is yours to supply: the caption county and estate number, each taker's relationship and will item, the verification signed by every personal representative (and, if an attorney represents you, their signature on the account too, under Md. Rule 6-134(a)), and the certificate of service naming each interested person served when you file (Md. Rule 6-417(d)).
Section 4 of 7.What a Maryland personal representative can be paid
Commissions are capped by Est. & Trusts §7-601: 9% of the first $20,000 of the property subject to administration, which is $1,800, plus 3.6% of the excess. That is a ceiling, and the Orphans' Court has discretion over what it allows, so you are not automatically owed the full amount. Ask the attorney whether estate income belongs in the compensable value. Payment follows either a court order under Md. Rule 6-416(a) or a filed Consent to Compensation (Form RW1138). Under the consent route, commissions plus attorney's fees face a combined ceiling. The commission is listed as an expense on Schedule 5.
Section 5 of 7.How a Maryland estate closes at the Orphans' Court
Maryland does not close estates on receipts and releases alone, and it has no refunding bond and no separate petition for discharge. Estates close on Orphans' Court approval of the final account filed with the county Register of Wills. Wait out the 6-month creditor window. Prepare the final account showing every receipt, expense, fee, and distribution. Pay the inheritance tax the register assesses (10% of the clear value passing to non-exempt beneficiaries), and keep a receipt or cancelled check for each distribution. Once the court approves the account and the 20-day exception window passes, the estate is closed.
The one shortcut is modified administration, for estates where every residuary taker qualifies and consents. Qualifying takers are typically the personal representative, inheritance-tax-exempt family members, or exempt trusts. Elect it within 3 months of appointment (Est. & Trusts §5-702). Under Md. Rule 6-455, neither Rule 6-402 nor Rule 6-417 then applies. A verified Final Report (Form RW1143) within 10 months replaces both, with distributions finished within 12 months.
- Wait out the 6-month creditor window, then prepare your final administration account for the Register of Wills showing every receipt, expense, fee, and the final distributions. There is no official court form for the account. The Registers of Wills publish a sample guide instead. Its suggested format is not required, but the information and documentation it describes are.
- Pay the inheritance tax the register assesses (10% of the clear value passing to non-exempt beneficiaries). The register collects it through the account/final-report process before distributions are complete.
- Get a signed receipt from each beneficiary (or keep the canceled check) for every distribution. The account must document where everything went.
- File the final account. Once the Orphans' Court approves it and the 20-day exception window passes, approval is final and the estate is closed automatically. Maryland has no separate petition for discharge.
- If you elected modified administration, skip the accounts entirely: file the verified Final Report (Form RW1143) within 10 months of appointment and finish distributions within 12 months. No court approval of the report is required.
Maryland closes estates through Orphans' Court approval of the final account (or the unapproved final report under modified administration) filed with the county Register of Wills. There is no informal receipt-and-release-only closing and no refunding-bond filing.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger keeps the estate's books and builds these documents from them. Recording is free, and the court-style Maryland documents preview free with your real numbers: an inventory package grouped the way RW1122 and RW1123 expect, and a seven-schedule account in the shape of Md. Rule 6-417. They are not court forms. The inventory package mirrors RW1122 and RW1123 so you can transcribe it line for line onto the official Register of Wills forms. The account has no official form to copy, so it carries the information Md. Rule 6-417 and the registers' sample guide describe, in the sample's layout. The estate's attorney should read both first. $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate.
Section 7 of 7.Questions Maryland executors ask
Is there an official form for a Maryland administration account?
No. The Judiciary's tip sheet says there is no form to use for an account, and the Registers of Wills publish a sample guide instead. Its suggested format is not required, but the information it describes is. Md. Rule 6-417 sets the contents.
When is the first Maryland administration account due?
Generally within 9 months after your appointment (Est. & Trusts §7-305). Until the final account is approved, each later account is generally due at whichever comes first: 6 months after the prior account's approval or 9 months after its filing (Md. Rule 6-417(a)). Confirm the exact due date, and any extension, with the estate's attorney.
Can Maryland beneficiaries sign a waiver instead of a court accounting?
Not on their own. Maryland estates close on Orphans' Court approval of the final account, so there is no receipt-and-release-only route. The closest thing is modified administration, elected within 3 months with every residuary taker's consent, which replaces the inventory and the accounts with a verified Final Report (Form RW1143) due within 10 months.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares. See also the Maryland estate inventory guide.
This page describes Maryland practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.