Kentucky Estate Accounting: An Executor's Guide
Kentucky calls the estate accounting a settlement, and much of what an executor here files changed on July 15, 2026. Here is what the District Court expects now.
Section 1 of 7.The two documents: the AOC-841 inventory and the AOC-846 settlement
Kentucky asks for two documents. The first is the inventory, form AOC-841, Inventory and Appraisement of Estate (Rev. 7-26). It has five numbered sections, in order: Real Property, Motor Vehicles, Personal Property, Cash and Cash Equivalents, Other. Each line carries a date-of-death value, and the form ends in one grand total, Total Estimated Value. There are no subtotals, no encumbrance column, and no oath or notary.
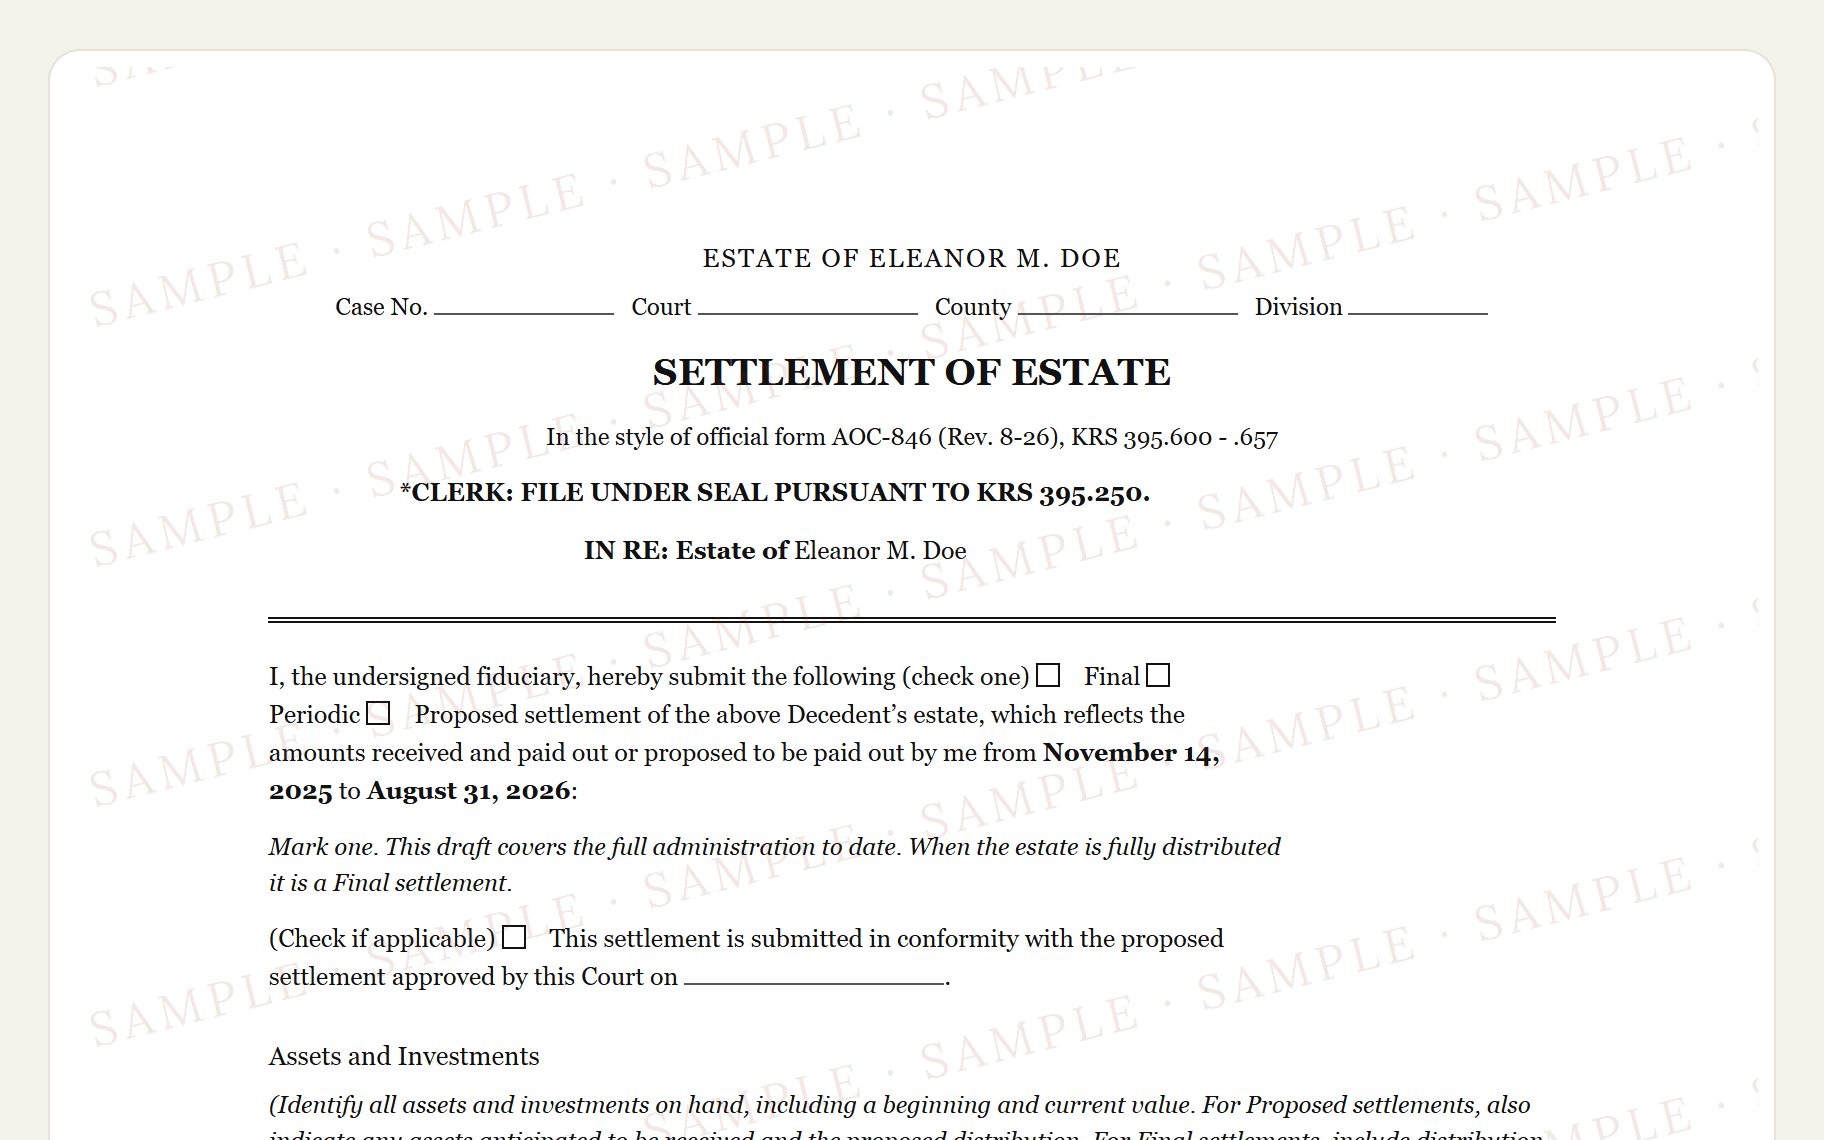
The second is the settlement, which is Kentucky's word for the accounting. The formal one is form AOC-846, Settlement of Estate (Rev. 8-26). Check one box, Final, Periodic, or Proposed, and give the period. Assets and Investments carries a beginning and a current value per item. Receipts and Disbursements covers everything since the last inventory or settlement. The bottom line reads BALANCE (ASSETS + RECEIPTS - DISBURSEMENTS). A final settlement adds a page listing unpaid creditors with allowed claims and creditors with disallowed claims (KRS 395.610(5)(b)), the fees paid to you and your attorney, and a death-tax checkbox.
Both carry the same clerk instruction at the top: file under seal. The inventory is confidential, and the clerk sends a copy to the Department of Revenue (KRS 395.250(1)(b)). Settlements come under the same provisions (KRS 395.250(6)).
Section 2 of 7.Kentucky's deadlines, with the statute behind each
- Day 90 (about 3 months)Inventory and appraisement of the estate (AOC-841)
Why
Under KRS 395.250, the personal representative generally must file the estate inventory (form AOC-841) with the District Court no later than 90 days after qualifying; the inventory is filed under seal and the court clerk transmits a copy to the Department of Revenue; confirm the exact due date and filing mechanics with your attorney. - Day 180 (about 6 months)Spousal renunciation window closes 6 months after probate
Why
KRS 392.080 lets a surviving spouse renounce the will and take the statutory share under KRS 392.020 instead, by filing an acknowledged renunciation with the clerk of the court that admitted the will to probate and with the county clerk within 6 months after the will is admitted to probate (approximated here as 180 days, anchored to your appointment, which in Kentucky is usually ordered at the same District Court hearing that probates the will; if probate came earlier, the true deadline is earlier too); the district court can extend the period by up to 6 more months on an application filed within the original 6, and a will contest brought within the window gives the spouse until 6 months after the contest is resolved; distributing before this window closes risks having to recover property if a renunciation is filed; confirm with your attorney whether a renunciation is possible in this estate. - Day 180 (about 6 months)Creditor claims bar date
Why
Under KRS 396.011, claims that arose before death are generally barred unless presented within 6 months after the personal representative's appointment, or 2 years after death if no one is appointed (the 6 months are approximated here as 180 days, so the true bar can fall a few days later), so calendar this bar date before paying claims or distributing anything; confirm the operative date and any exceptions with your attorney. - Day 180 (about 6 months) · earliest possibleEarliest date to file an informal final settlement
Why
Under KRS 395.605(3), an informal final settlement (forms AOC-850/AOC-851, with verified waivers from the beneficiaries) generally may be filed any time after 6 months from the fiduciary's appointment, not before (approximated here as 180 days, so the true earliest date can fall a few days later); confirm the timing and whether the informal route fits this estate with your attorney. - Day 730 (about 2 years)First periodic settlement, if the estate is still open
Why
Under KRS 395.610(1)-(3), if administration is still open 2 years after appointment, the fiduciary generally must file a periodic settlement with the District Court accounting for all receipts and disbursements since the last inventory or settlement, and annually thereafter until everything is distributed; confirm whether this applies and the exact date with your attorney.
- Day 270 (about 9 months)5% early-payment discount on Kentucky inheritance tax
Why
Under KRS 140.210, paying the inheritance tax early generally earns a 5% discount: within 9 months of death for deaths before July 1, 2026, or within 14 months for deaths on or after that date; this entry uses the shorter 9-month window to be safe. Confirm whether tax is owed and which window applies with your attorney. - Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax; confirm applicability and timing with your attorney. - Day 540 (about 18 months)Kentucky inheritance tax return and payment, if required
Why
Under KRS 140.210 and 140.160, for deaths before July 1, 2026 the Kentucky inheritance tax is generally payable within 18 months of death, and the return, when one is required, is filed within the same 18 months or with the payment; for deaths on or after July 1, 2026 both deadlines are 24 months, with interest running afterward; this entry uses the shorter 18-month date to be safe; confirm whether a return is required, whether tax is owed, and which deadline applies with your attorney.
The AOC-841 inventory is generally due 90 days from the time you qualify (KRS 395.250(1)(a), amended effective July 15, 2026). A guide that says 60 days is quoting the old statute. Filing late starts the KRS 395.255 track, which ends at $100 for each day of unexcused failure (KRS 395.990).
Read the full explanation
Claims arising before death are generally barred unless presented within 6 months after appointment, or within 2 years after death if no one is appointed (KRS 396.011). Six months is also the earliest an informal final settlement may be filed (KRS 395.605(3)).
If administration is still open 2 years from appointment, the fiduciary generally must file a periodic settlement covering all receipts and disbursements since the last inventory or settlement, and then one a year until everything is distributed (KRS 395.610(1)-(3)).
Kentucky inheritance tax, if owed, is generally payable within 18 months of death for deaths before July 1, 2026, and within 24 months for deaths on or after, with a 5% discount for paying within 9 or 14 months respectively (KRS 140.210). Both settlement routes have a checkbox stating that the tax is paid or the estate is exempt, so unresolved tax holds the estate open. Confirm with your attorney what applies.
Section 3 of 7.Two ways to close: the waiver route and the formal settlement
Ask about the Kentucky informal settlement first. Under KRS 395.605, if every beneficiary is under no legal disability and signs a notarized affidavit of waiver (form AOC-851, one each), you file an Application for Informal Final Settlement (form AOC-850) under penalty of perjury, any time after 6 months from your appointment. One exception: a nonresiduary legatee who has already received and receipted for the legacy does not need to sign a waiver. A canceled check or signed receipt attached to the settlement is enough (KRS 395.605(2)(c); AOC-850 item 2). The court shall not require notice to any person or a hearing. A beneficiary under a disability does not automatically end the route. The court can still allow the informal filing if it finds that filing serves that person's best interests (KRS 395.605(6)).
That application contains no accounting. It states that six months have passed, that the estate is solvent, that claims and debts are paid or provided for, that death taxes are handled, that court costs are paid, and what the attorney charged. Any beneficiary may still request an accounting before signing (KRS 395.605(2)(b)). A sole beneficiary who has received their share applies alone, with no waivers needed (KRS 395.605(1)).
If someone will not sign, or the court requires it, you file the formal AOC-846 settlement with its hearing and disposing orders (AOC-846.1, AOC-846.2). The District Judge reviews it, the clerk publishes notice at least 10 days before the hearing, and exceptions come before it (KRS 395.620 through 395.625). Keep the closing order. On the informal route the court may enter an order discharging you and any surety on approval (KRS 395.605(5)); that order is AOC-850.1. On the formal route it is the Settlement Order (AOC-846.2), which closes the estate and relieves you and any surety.
- Hold off on closing until 6 months after your appointment. An informal final settlement cannot be filed before then (KRS 395.605(3)), and the creditor-claims window is still running (KRS 396.011).
- If everyone has been paid and is cooperative, take the informal route: have each beneficiary sign a verified (notarized) waiver of formal settlement (form AOC-851), then file the Application for Informal Final Settlement (form AOC-850) with the District Court under KRS 395.605, attaching proof the inheritance tax was handled; a nonresiduary legatee's signed receipt or canceled check works in place of a waiver.
- If you are the estate's only beneficiary and have received your share, you can file the informal final settlement on your own application signed under penalty of perjury, with no waivers needed (KRS 395.605(1)).
- If anyone will not sign, file a formal final settlement instead (form AOC-846, with hearing and order forms AOC-846.1/846.2): a complete account of every receipt and disbursement with supporting documentation, distributions, and the fees you and your attorney were paid; the court gives notice, holds any hearing, and confirms it (KRS 395.610-395.625).
- Once the court approves the settlement, get the order discharging you and your surety, and keep it with the estate records. On the informal route that is the order accepting the settlement (KRS 395.605(5)); on the formal route it is the court's Settlement Order (form AOC-846.2), which closes the estate and relieves you and any surety (KRS 395.620, 395.630).
Probate sits in the Probate Division of Kentucky District Court in the county where the personal representative qualified. Since July 15, 2026, the inventory and formal settlements (AOC-841/AOC-846) are confidential and filed under seal (KRS 395.250(1)(b), (6), 2026 Ky. Acts ch. 134); the informal-settlement forms carry no seal instruction.
Section 4 of 7.What Kentucky pays an executor
KRS 395.150 sets the ceiling: compensation shall not exceed five percent (5%) of the value of the personal estate of the decedent, plus five percent (5%) of the income collected. It is a statutory maximum that the district court approves. Courts commonly allow it in full for a complete administration, but it is never automatic. Real estate passing directly to heirs sits outside the base. Anything above the cap takes proof submitted for unusual or extraordinary services, or for real-estate or tax work (KRS 395.150(2)). A final settlement discloses the amounts paid to the fiduciary and the attorney (KRS 395.610(5)(c)). The statute asks for figures, not a description of the work.
Section 5 of 7.What only you can supply
Software can shape the page and carry the numbers. It cannot know the caption: Case No., Court, County, and Division. (Kentucky probate sits in District Court in the county where you qualified.) It also cannot know each vehicle's VIN, each account's type, or an address the description does not carry. Brokerage and business interests print under Other. Whether securities belong there or under Cash and Cash Equivalents is a call the form leaves open.
It also cannot decide what to leave off. Property passing outside probate is generally excluded: survivorship joint property, payable- and transfer-on-death accounts, and insurance or retirement money with living named beneficiaries. That is consistent with KRS 391.360 and 395.015(3)(b), though the inventory statute itself lists no exclusions. Ask your attorney when an item is a close call. Property found later goes on an amended inventory (KRS 395.250(4)).
Section 6 of 7.Where ExecutorLedger fits
Recording is free for as long as the estate takes: every receipt and disbursement with date and payee, distributions per beneficiary, and a running balance that checks itself as you go. ExecutorLedger builds Kentucky court-style documents from those records, an inventory shaped like AOC-841 and a settlement shaped like AOC-846, ready to transcribe onto the official forms. They are not court forms, and the estate's attorney should read them first. Every document previews free with your real numbers, and $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate.
Section 7 of 7.Questions Kentucky executors ask
When is the Kentucky AOC-841 inventory due?
Generally no later than 90 days from the time you qualify as personal representative (KRS 395.250(1)(a), amended effective July 15, 2026). It is filed under seal, and the clerk sends a copy to the Department of Revenue. Guides saying 60 days quote the old statute.
What is a Kentucky informal settlement, and can I use one?
It is the KRS 395.605 route: an application (AOC-850) signed under penalty of perjury, with a notarized waiver (AOC-851) from every beneficiary, or your application alone as a sole beneficiary who has received their share. One exception: a nonresiduary legatee who has already received and receipted for the legacy does not need to sign a waiver. The application may be filed any time after 6 months from appointment, with no notice and no hearing, and it includes no accounting. Whether it fits is your attorney's call.
What goes on the AOC-846 settlement of estate?
The Final, Periodic, or Proposed checkbox; the period; assets with beginning and current values; receipts and disbursements since the last inventory or settlement, with supporting documentation (not required for a Proposed settlement); and a balance of assets plus receipts minus disbursements. A final settlement adds the creditor lists, the fees paid, and the death-tax checkbox.
If every beneficiary signs a waiver, do I still need Kentucky executor accounting?
The informal filing carries no accounting, but any beneficiary may request one before signing (KRS 395.605(2)(b)). You also cannot state under penalty of perjury that the estate is solvent and that claims, debts, and court costs are paid without a complete record behind you. If a residuary beneficiary refuses, you are on the AOC-846 track.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares. See also the Kentucky estate inventory guide.
This page describes Kentucky practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.