Florida Estate Accounting: An Executor's Guide
In Florida you are the personal representative, and the accounting is what shows you did the job. Here is the shape Florida expects, the deadlines that drive it, and what closing takes.
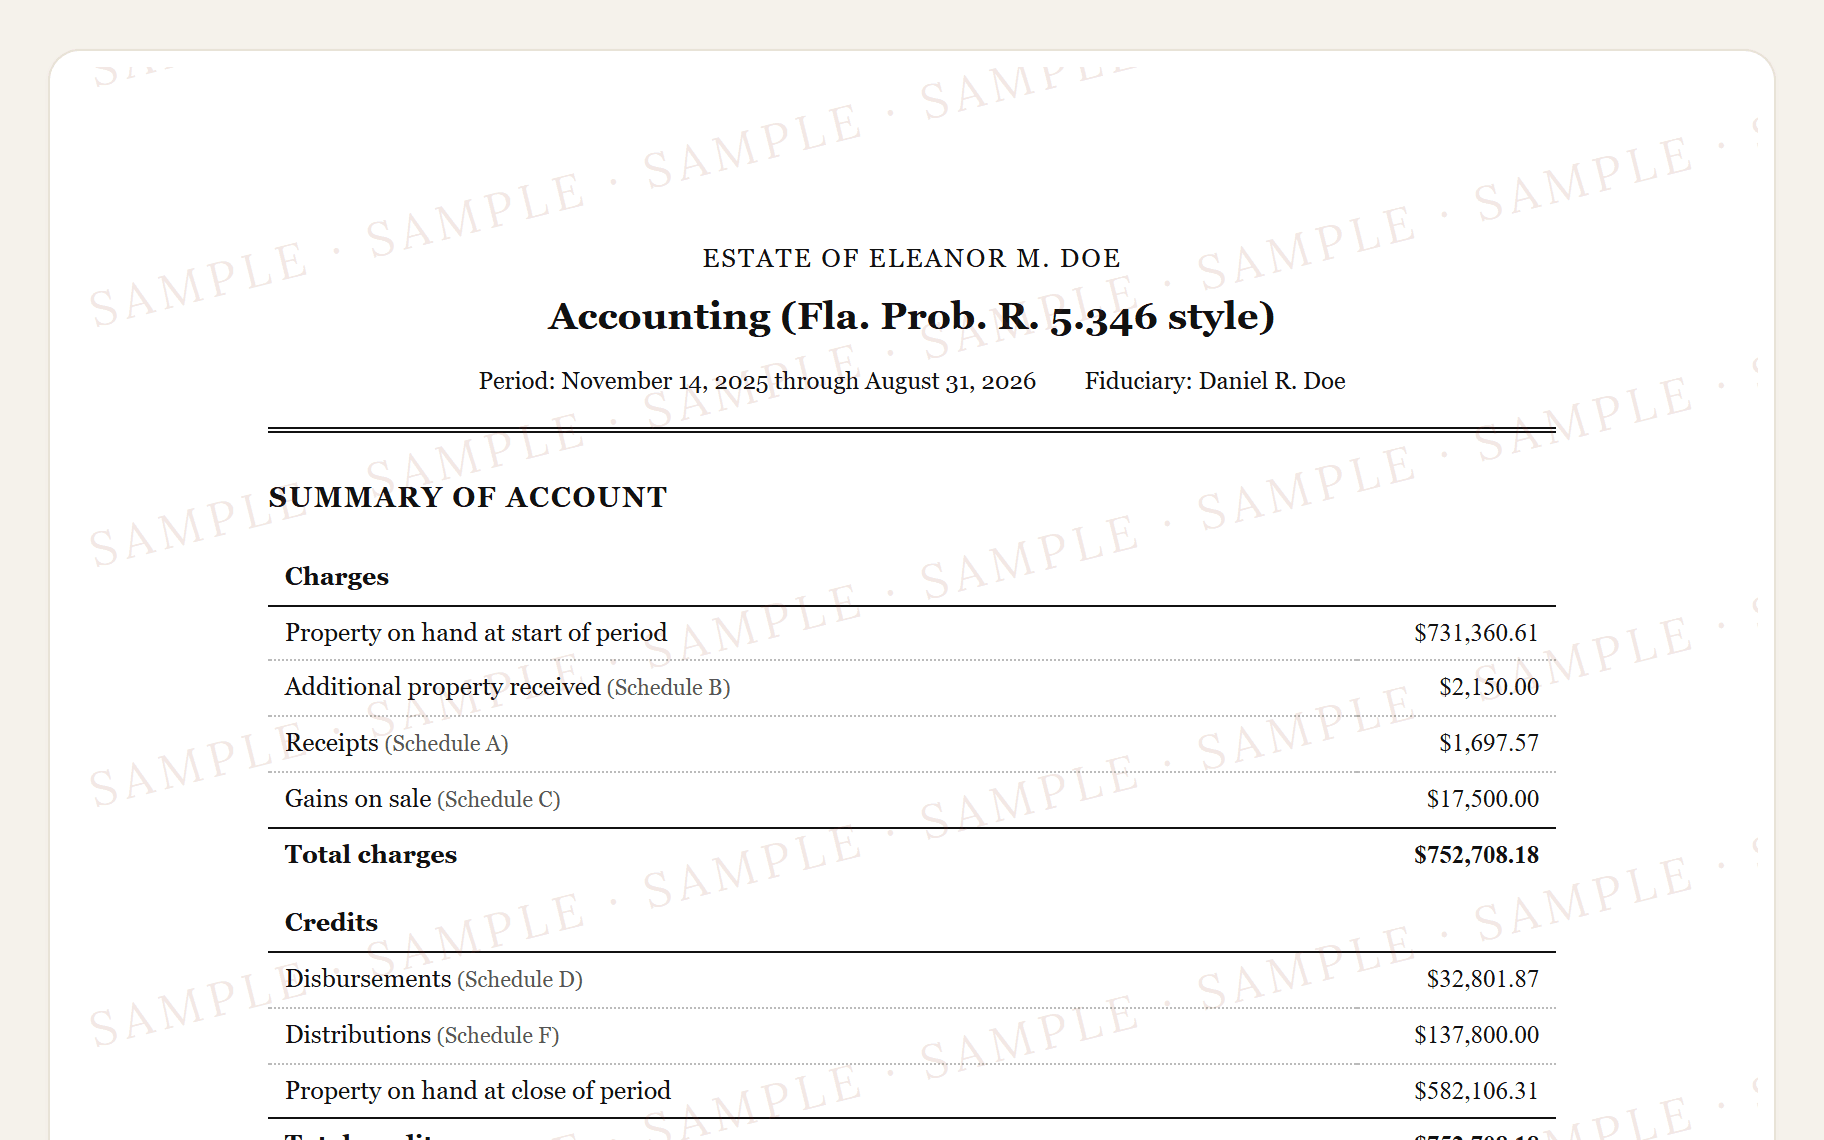
Section 1 of 7.The accounting Florida expects under Rule 5.346
A Florida probate accounting is built like every estate accounting. Charges are everything you were answerable for. Credits are everything that left or remains. The two balance to the penny. What sets the Florida version apart from a plain informal accounting is the columns. Under Prob. R. 5.346, Florida practice accounts for the estate's own money and the money it earned while open separately, so principal and income never blur into one number.
Get that split right early. Deciding a year later whether a deposit was principal or income, from bank statements alone, is close to impossible. Tag each entry the day it happens. Behind the summary sit the usual schedules: receipts, property found after the inventory, disbursements, gains and losses on sales, distributions to each beneficiary, and the property still on hand.
The inventory comes first and is its own filing. Fla. Prob. R. 5.340 puts it typically 60 days after letters of administration issue, and the court can extend it. Confirm the exact date with your attorney. Its values become the opening balance of the accounting, so treat it that way.
Section 2 of 7.Florida's deadlines, with the citation behind each
- Day 30 (about 1 month)Send the Notice of Administration to the surviving spouse and beneficiaries
Why
Fla. Stat. §733.212 requires prompt service on the surviving spouse and beneficiaries. About 30 days is a common target, but the statute says 'promptly,' so confirm timing with your attorney. - Day 30 (about 1 month)Publish the Notice to Creditors in a local paper
Why
Fla. Stat. §733.2121 requires prompt publication once a week for two weeks, which starts the 3-month creditor claim window. The statute sets no fixed day count, so the 30-day date here is only a reminder to publish promptly; confirm timing and the newspaper with your attorney. - Day 60 (about 2 months)File the estate inventory with the court
Why
Under Fla. Prob. R. 5.340, this is typically due 60 days after letters of administration issue, and the court can extend it; confirm the exact date with your attorney. - Day 365 (about 1 year)File the final accounting and petition for discharge
Why
Under Fla. Prob. R. 5.400, this is typically due 12 months after letters issue (later if a federal estate tax return is due), and courts routinely extend it; confirm the schedule with your attorney.
- Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability (Florida has no separate estate tax); confirm with your attorney or CPA whether one is needed and whether an extension was filed. - Day 730 (about 2 years)Spousal elective share window closes no later than 2 years after death
Why
Under Fla. Stat. §732.2135, the surviving spouse's election to take the elective share (30 percent of the elective estate under §§732.201 and 732.2065) must be filed by the earlier of 6 months after the notice of administration is served on the spouse or 2 years after death; this date is the 2-year outer bound (approximated here as 730 days), and service of the notice usually closes the window sooner; the court can extend the time for good cause, so distributing before the window closes risks having to recover property if an election is filed; confirm with your attorney whether an election is possible in this estate. - Day 730 (about 2 years)Two-year cutoff for all creditor claims
Why
Under Fla. Stat. §733.710, claims not brought within 2 years of death are generally barred regardless of notice; calendar it, and confirm how it applies to this estate with your attorney.
Notice of Administration. Fla. Stat. §733.212 requires prompt service on the surviving spouse and beneficiaries. About 30 days is a common target, but the statute says promptly, so confirm timing with your attorney.
Read the full explanation
Notice to Creditors. Fla. Stat. §733.2121 requires prompt publication in a local paper once a week for two weeks, which starts the 3-month creditor claim window. The statute sets no fixed day count, so the 30-day date here is only a reminder to publish promptly. Confirm the timing and the newspaper with your attorney.
The two-year cutoff. Under Fla. Stat. §733.710, claims not brought within 2 years of death are generally barred regardless of notice. Calendar it, and confirm how it applies to this estate with your attorney.
Federal estate tax return, if one is required. Form 706 is due 9 months after death under IRC §6075, but only if the gross estate exceeds the federal exemption or the estate elects portability. Florida has no separate estate tax. Confirm with your attorney or CPA whether a return is needed and whether an extension was filed.
The final accounting and petition for discharge. Fla. Prob. R. 5.400 puts these typically 12 months after letters issue, later if a federal estate tax return is due, and courts routinely extend. Confirm the schedule with your attorney.
Section 3 of 7.What a Florida personal representative is paid
Fla. Stat. §733.617 calls a fee presumed reasonable at 3% of the first $1,000,000 of compensable value, then 2.5% to $5,000,000, 2% to $10,000,000, and 1.5% above. Compensable value means the inventory value of the probate assets plus the income the estate earned during administration. That is one more reason to keep the columns straight.
Presumed does not mean fixed. The court can still raise or lower the fee based on how the work went. If the will sets the personal representative's pay, the will usually controls, so have the attorney read it. The fee is also taxable income to you. If you are also the main beneficiary, waiving the fee and taking more as inheritance is often the better choice. Make that call with the attorney and a tax preparer.
Section 4 of 7.How Florida estates usually close
The pattern is short. File the final accounting and the petition for discharge, and serve them on interested persons. Wait out the objection period. Make the distributions in the plan and collect receipts. Then obtain the order of discharge. Your liability ends with that order, so don't treat the last check as the finish.
Waivers can substitute when everyone signs. The accounting is still needed, because it is what the beneficiaries are signing off on, and they can ask to see it complete and clear first. Which route your estate takes is a question for its attorney.
- File the final accounting and petition for discharge, and serve them on interested persons (waivers can substitute when everyone signs).
- Wait out the objection period.
- Make the distributions in the plan and collect receipts.
- Obtain the order of discharge. That's what ends your liability.
Section 5 of 7.What software can prepare, and what only you can supply
Software can carry the arithmetic. From a ledger kept as you go, a Florida personal representative accounting can be generated whole: the schedules, the principal and income columns, the summary balanced to the penny, and a per-beneficiary distribution statement. Interim accountings come from the same records.
Software cannot supply judgment. It cannot read the will. It does not track mortgages or liens, so real property values print gross, and if your filing shows them net you subtract when transcribing. It cannot decide what belongs in the inventory. What is probate property and what passes outside it turns on facts about this estate, and that is the attorney's call. The case details, the fee you request, and anything the will directs are yours.
One more limit. A generated document follows the general style of the named Florida format. It is not a court form, and courts differ. It gives your attorney a complete, correctly structured starting point, ready to transcribe. It does not replace their review.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger is Florida executor accounting software. Recording is free for as long as the estate takes. Every court-style Florida document previews free and complete with your real numbers, under a watermark. $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate. Co-executors, the attorney, and beneficiaries get free seats.
Section 7 of 7.Questions Florida executors ask
What is a Florida probate final accounting?
It is the accounting you file with the petition for discharge, served on interested persons. Fla. Prob. R. 5.400 puts it typically 12 months after letters issue, later if a federal estate tax return is due, and courts routinely extend. It shows everything the estate received and paid, balances charges against credits, and supports the distributions in the plan.
When is the Florida estate inventory due?
Fla. Prob. R. 5.340 puts the inventory typically 60 days after letters of administration issue, and the court can extend it. Confirm the exact date with your attorney. Take care with it, because the inventory values become the opening balance of every accounting that follows.
Is there a Florida estate accounting form I can just fill in?
What Florida practice expects is an accounting in the Prob. R. 5.346 shape, with principal and income in separate columns. ExecutorLedger produces a court-style document in that shape from your ledger, ready to transcribe. It is not a court form. Ask the attorney what your circuit wants to see.
Can Florida beneficiaries waive the accounting?
Waivers can substitute when everyone signs. The accounting still matters, because it is what the beneficiaries are agreeing to. Either way the order of discharge is what ends your liability, so do not treat the last distribution as the end. Ask the attorney whether waivers work here.
How much does a Florida personal representative get paid?
Fla. Stat. §733.617 treats 3% of the first $1,000,000 of compensable value as presumed reasonable, then 2.5% to $5,000,000, 2% to $10,000,000, and 1.5% above. Compensable value is the inventory value of the probate assets plus income earned during administration. The court can raise or lower it for how the work went, and if the will sets the fee, the will usually controls.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes Florida practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.