Connecticut Estate Accounting: An Executor's Guide
Connecticut asks an executor for two documents: an inventory early, and a financial report or account at the end. Here is what each one is, when it is due, and where the rules leave the judgment to you.
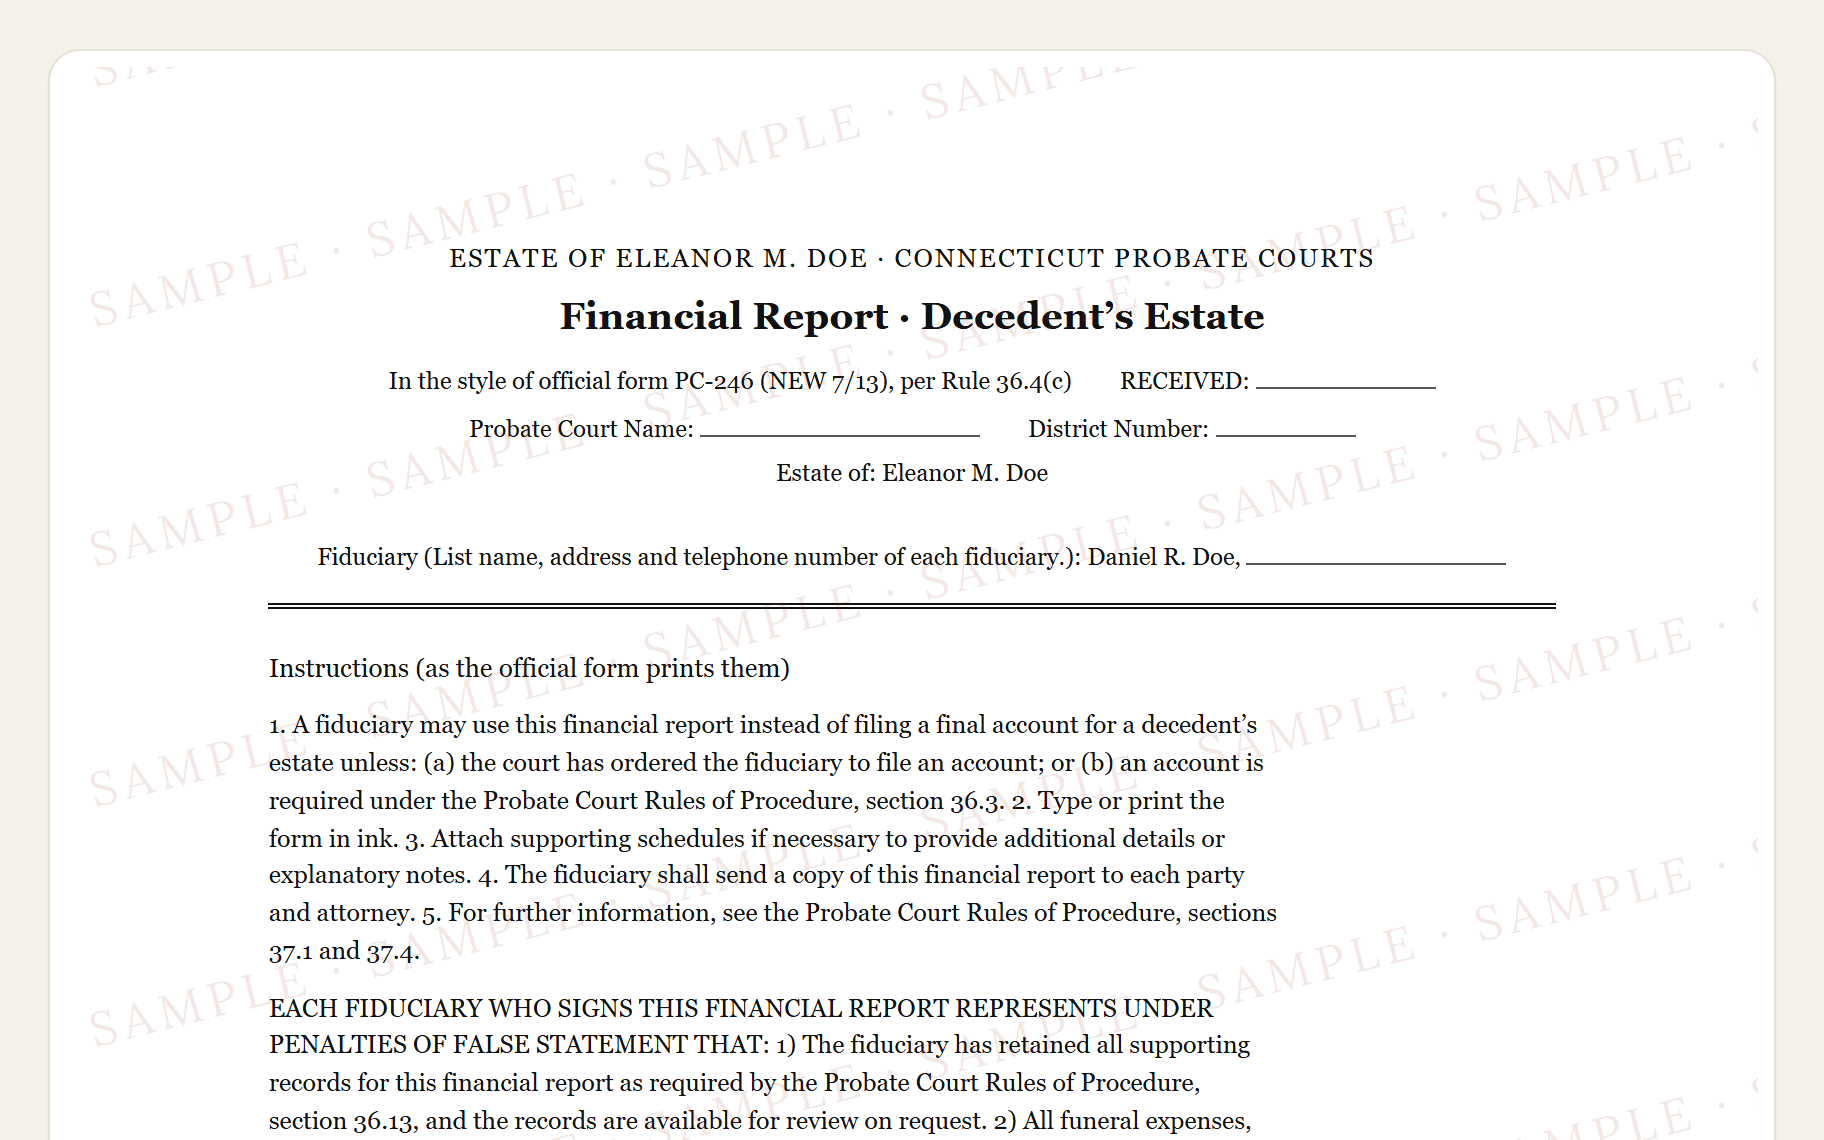
Section 1 of 7.The PC-2407 inventory and the PC-246 financial report
Connecticut usually calls the closing document a financial report rather than an accounting. Rule 36.1 of the Probate Court Rules of Procedure lets a fiduciary account by submitting a financial report instead of a full account, and the Probate Court Administrator's User Guide says at Step 8: "In most cases, the simpler financial report, Financial Report/Decedent's Estate, PC-246, can be used." The fuller alternative is PC-242, the Decedent's Estate Administration Account (Short Form).
The inventory comes first. Step 4 of the same guide says: "File Inventory, PC-2407, within two months of appointment as fiduciary." It lists solely owned property at date-of-death fair market value, which is also your accounting's opening figure, since rule 36.14(a)(1) sets fiduciary acquisition value at that same number. Connecticut lists a second inventory form, PC-440, alongside PC-2407, with no deprecation notice on either. PC-440 is still a valid filing vehicle, and the two bodies are nearly identical. The User Guide names PC-2407 for decedents' estates, so that is the shape to work from.
A full account is required instead only when the court orders one, or when principal and income must be accounted for separately (rule 36.3). Rule 38.1(b) triggers that when the will funds a trust with differing income and principal interests, creates a life interest in intangible personal property, or the surviving spouse elects against the will (C.G.S. § 45a-436). Those are will-reading questions for the estate's attorney.
Section 2 of 7.Connecticut probate deadlines, with the citation for each
- Day 59 (about 2 months)File inventory with the Probate Court
Why
Under Conn. Gen. Stat. §45a-341, the inventory, listing probate assets at fair market value as of death, generally must be filed with the Probate Court (form PC-2407, which the Probate Courts' current User Guide names for decedents' estates; the older PC-440 remains a valid vehicle and the two are nearly identical) within 2 months after you qualify as fiduciary (approximated here as 59 days from your letters date), and the court can extend that to 4 months for cause; confirm the exact due date with your attorney. - Day 59 (about 2 months)Record notice of appointment in the land records (if CT real estate)
Why
Under Conn. Gen. Stat. §45a-322, if the decedent owned Connecticut real estate, you generally must lodge a certificate of the death and your appointment (Notice for Land Records, PC-251) with the town clerk of each town where the property is located within 2 months after qualifying (approximated here as 59 days from your letters date); confirm whether this applies and the timing with your attorney. - Day 150 (about 5 months)Spousal statutory share window closes 150 days after the decree admitting the will is mailed
Why
Under Conn. Gen. Stat. §45a-436, a surviving spouse may elect a statutory share in place of what the will provides, a life estate of one-third in value of all property passing under the will after debts and charges, by filing a written notice of intention with the Probate Court not later than 150 days after the mailing of the decree admitting the will to probate, and a spouse who does not file in time is barred; the statute provides no extension. The clock runs from the mailing of that decree rather than from your appointment, and the two typically issue together, so this timeline anchors it to your letters date; distributing before this window closes risks having to recover property if an election is filed, so confirm the operative date and whether an election is possible in this estate with your attorney. - Day 150 (about 5 months) · earliest possible150-day creditor claim period ends (safe-harbor to pay and distribute)
Why
Under Conn. Gen. Stat. §45a-356(a), once 150 days have passed since appointment of the first fiduciary, you can generally pay claims and make good-faith distributions without personal liability for claims presented later; this is typically a safe harbor rather than an absolute bar (late claims can still reach beneficiaries under §45a-368), so confirm the operative date and whether it is safe to distribute with your attorney. - Day 210 (about 7 months)File Return of Claims and List of Notified Creditors (PC-237)
Why
Under Conn. Gen. Stat. §45a-361, within 60 days after the 150-day claim period ends (generally about 210 days after appointment of the first fiduciary), you typically must file a signed return listing everyone you notified under §45a-357 and every claim presented, stating how far each was allowed or rejected; confirm the exact date with your attorney. - Day 455 (about 15 months)Annual status update to the court if no financial report or account has been filed (PC-286)
Why
Under Conn. Probate Court Rules of Procedure rule 30.21, if you have not yet filed an interim or final financial report or account, a status update is generally due not later than 3 months after the first anniversary of your appointment (and on each anniversary after that), stating distributions made, assets on hand, and why administration is not finished; confirm whether this applies with your attorney.
- Day 180 (about 6 months)Connecticut estate tax return (CT-706 NT or CT-706/709), required for every estate
Why
Under Conn. Gen. Stat. §12-392, a Connecticut estate tax return is generally due 6 months after death for every estate, even when no tax is owed: Form CT-706 NT is typically filed with the Probate Court for nontaxable estates, while taxable estates file CT-706/709 with the Department of Revenue Services plus a copy to the court; unpaid tax accrues interest from the due date, and statutory probate-court fees start accruing 0.5% monthly interest 30 days after this due date if the return has not been filed (§45a-107), so confirm which form applies and the exact date with your attorney. - Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax; confirm applicability and timing with your attorney.
The inventory is generally due within two months, and the court can extend it to four months from qualification for cause (§ 45a-341). The statute runs from acceptance of the bond or other qualification of the fiduciary; the form says date of appointment. Connecticut real estate also brings a land-records notice (PC-251) to the town clerk of each town where the property sits, generally within two months (§ 45a-322).
Read the full explanation
Creditors get 150 days from the appointment of the first fiduciary. After that, § 45a-356(a) generally lets you pay claims and make good-faith distributions without personal liability for claims presented later. It is typically a safe harbor rather than an absolute bar: a late claim can still reach beneficiaries under § 45a-368. Confirm the operative date, and whether it is safe to distribute, with the estate's attorney. Within 60 days after the period ends, you generally file the Return of Claims and List of Notified Creditors, PC-237 (§ 45a-361).
A Connecticut estate tax return is generally due six months after death for every estate, even when no tax is owed (§ 12-392): CT-706 NT to the Probate Court for nontaxable estates, CT-706/709 to the Department of Revenue Services for taxable ones, with a copy to the court. Probate court fees then start accruing 0.5% monthly interest 30 days after that due date if the return has not been filed (§ 45a-107).
The report itself has no fixed deadline, and three sources frame it differently. Rule 30.19(a) is event-triggered: it goes in when settlement of the estate is complete, or when you resign or are removed. Form PC-286 prints its own expectation, "The financial report or account is due within 15 months of the appointment of the fiduciary," which no statute or rule anchors, and the User Guide says usually within 12 months of death. With nothing filed, rule 30.21 generally wants a status update three months after your first appointment anniversary, then yearly.
Section 3 of 7.What Connecticut pays an executor
Connecticut has no executor fee schedule. No percentage appears in its statutes or the Probate Court rules. Executors get reasonable compensation under common law (Hayward v. Plant, 98 Conn. 374, 119 A. 341 (1923)), and rule 39 requires the court to decide whether fiduciary fees are reasonable when it reviews the report or account, whether or not anyone objects. You may ask the court to approve a fee arrangement before the work (rule 39.1). Percentages you hear locally are custom rather than law. The court may ask for a task statement addressing the nine Hayward factors (rule 39.2), so keep a record of the work behind the number. Keep your fee separate from your costs, too: PC-246 prints "Fiduciary fees:" and "Fiduciary disbursements:" on separate lines.
Section 4 of 7.How a Connecticut estate closes
You file the final report (PC-246) or account (PC-242), send a copy to every party and attorney, and certify on the form that you did. Each beneficiary is asked to sign a waiver of the right to a hearing, PC-244A for a report and PC-245 for an account; with waivers the court can approve without anyone appearing. After approval and the order of distribution, you distribute exactly as approved and keep proof. If the court directs it, the Affidavit of Closing of Estate (PC-213) follows within 30 days after the last assets go out.
Those waivers do not release anyone. Any release runs to you, and only by decree: when the court approves the report it may enter a decree releasing you and any bond sureties from further liability for the items shown (§ 45a-176). PC-246's request clause is where you ask for it. Beneficiaries stay liable up to the value of what they received for the estate's unpaid expenses, taxes and claims (§ 45a-368), within the limits of §§ 45a-369 and 45a-370, and generally until the earlier of two years from death (or, for a claim arising after death, two years from when it arose) or the claim's own limitation period (§ 45a-375).
- When administration is complete, usually within about 12 months of death, file a final financial report (form PC-246) with the Probate Court, or the fuller administration account (PC-242) if the estate needs one (for example, the will funds a trust with differing income and principal interests or creates a life interest in intangible personal property, or the surviving spouse elects against the will). Send a copy to every party and attorney and certify on the form that you did.
- Ask each beneficiary to sign a waiver of the right to a hearing (PC-244A for a financial report, PC-245 for an account) confirming they received and reviewed it. With waivers on file the court can approve without anyone appearing; otherwise it holds a hearing or uses 'streamline' notice.
- After the court approves the report and orders distribution, distribute the remaining assets exactly as approved and collect proof of each distribution.
- If the court directs it, file the Affidavit of Closing of Estate (PC-213) within 30 days after distributing the last assets, reconciling any reserve and post-report transactions. That affidavit is effectively your final act as fiduciary.
Everything runs through the regional Connecticut Probate Court. There is no separate petition for discharge in routine estates: approval of the final financial report or account plus the affidavit of closing ends the fiduciary's role, and if a probate bond was posted the court sends the surety a certificate terminating it. There is no sworn UPC §3-1003-style closing statement filed in lieu of court review.
Section 5 of 7.What only you can supply
Real property is the one section Connecticut nets: address, the decedent's interest, fair market value, unpaid mortgage balance, and net value, reported as zero if the mortgage is higher. Attach a copy of the recorded deed. Everything else stays gross, so a car loan is not netted against the car. Only you can give each vehicle's year, make, model and VIN, each bank account's last four digits, and per-security detail for a brokerage account, where attaching the date-of-death holdings statement is the practical answer. Leave off real property outside Connecticut, joint property with rights of survivorship, and beneficiary-designated assets. A tenant-in-common fractional share is included.
On the report, the will-section column, the reserve, the court name and district number, and the certification's recipient list are yours. The PC-237 claims line prints the ledger's own debts-and-claims total, but only your filed PC-237 return governs that figure, so use the return's number if the two differ. The fair market value of in-kind distributions on their distribution date is also yours (rule 37.4(a)), unless every beneficiary in the class takes a proportionate share of each asset, in which case fiduciary acquisition value may be shown instead (rule 37.4(b)). The arithmetic is the ledger's. A financial report also need not balance the way an account must (rule 36.2(3)), while a PC-242 account foots section 1 against section 2 and carries a cash reconciliation that balances on its own (rule 38.5(b)).
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger keeps the ledger and builds the documents from it. Recording is free for as long as the estate takes, and the Connecticut documents, an inventory shaped like PC-2407 and a financial report shaped like PC-246, preview free with your real numbers. $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate. They are court-style documents, not court forms, laid out to be transcribed line for line onto the official PC forms the Probate Courts publish free at ctprobate.gov. The estate's attorney should read the report before it is filed.
Section 7 of 7.Questions Connecticut executors ask
Do I file a PC-246 financial report or a full Connecticut fiduciary account?
The financial report is the default path (rule 36.1). An account is required instead only when the court orders one, or when rule 38.1(b) makes you account for principal and income separately: a will-funded trust with differing income and principal interests, a life interest in intangible personal property, or a spousal election against the will. All three turn on the will, so confirm with the estate's attorney.
When is the CT PC-2407 inventory due?
Generally within two months. C.G.S. § 45a-341(b)(1) measures from acceptance of the bond or other qualification of the fiduciary, while the form and User Guide say from the date of appointment, and the court can extend to four months from qualification for cause. Send a copy to each party and attorney and complete the certification.
Is there a hard deadline for the Connecticut probate financial report?
Not in the statutes or rules. Rule 30.19(a) ties the final report or account to completing settlement, or to your resignation or removal. Form PC-286 prints its own expectation of 15 months from appointment and the User Guide says usually within 12 months of death, but no statute or rule anchors either number.
How much can I pay myself as executor in Connecticut?
A reasonable amount, judged case by case. There is no statutory or court-adopted percentage schedule; compensation rests on common law (Hayward v. Plant, 98 Conn. 374 (1923)), and rule 39 requires the court to review whether fiduciary fees are reasonable even if nobody objects. You can ask the court to approve a fee arrangement in advance (rule 39.1).
Does a signed PC-244A waiver release me from liability?
No. PC-244A and PC-245 confirm the beneficiary got a copy, waive notice and the right to a hearing, and state no objection to approval. The release comes from the court: on approving a financial report it may release the fiduciary and any bond sureties from further liability for the items shown (C.G.S. § 45a-176). Beneficiaries are not released (§ 45a-368).
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares. See also the Connecticut estate inventory guide.
This page describes Connecticut practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.