California Estate Accounting: An Executor's Guide
California probate runs on dates that start the day your letters issue. It ends at a hearing where a judge signs the order that lets you distribute, either with the accounting or with waivers of account signed by every beneficiary. Here is what the state asks of an executor, and what the job pays.
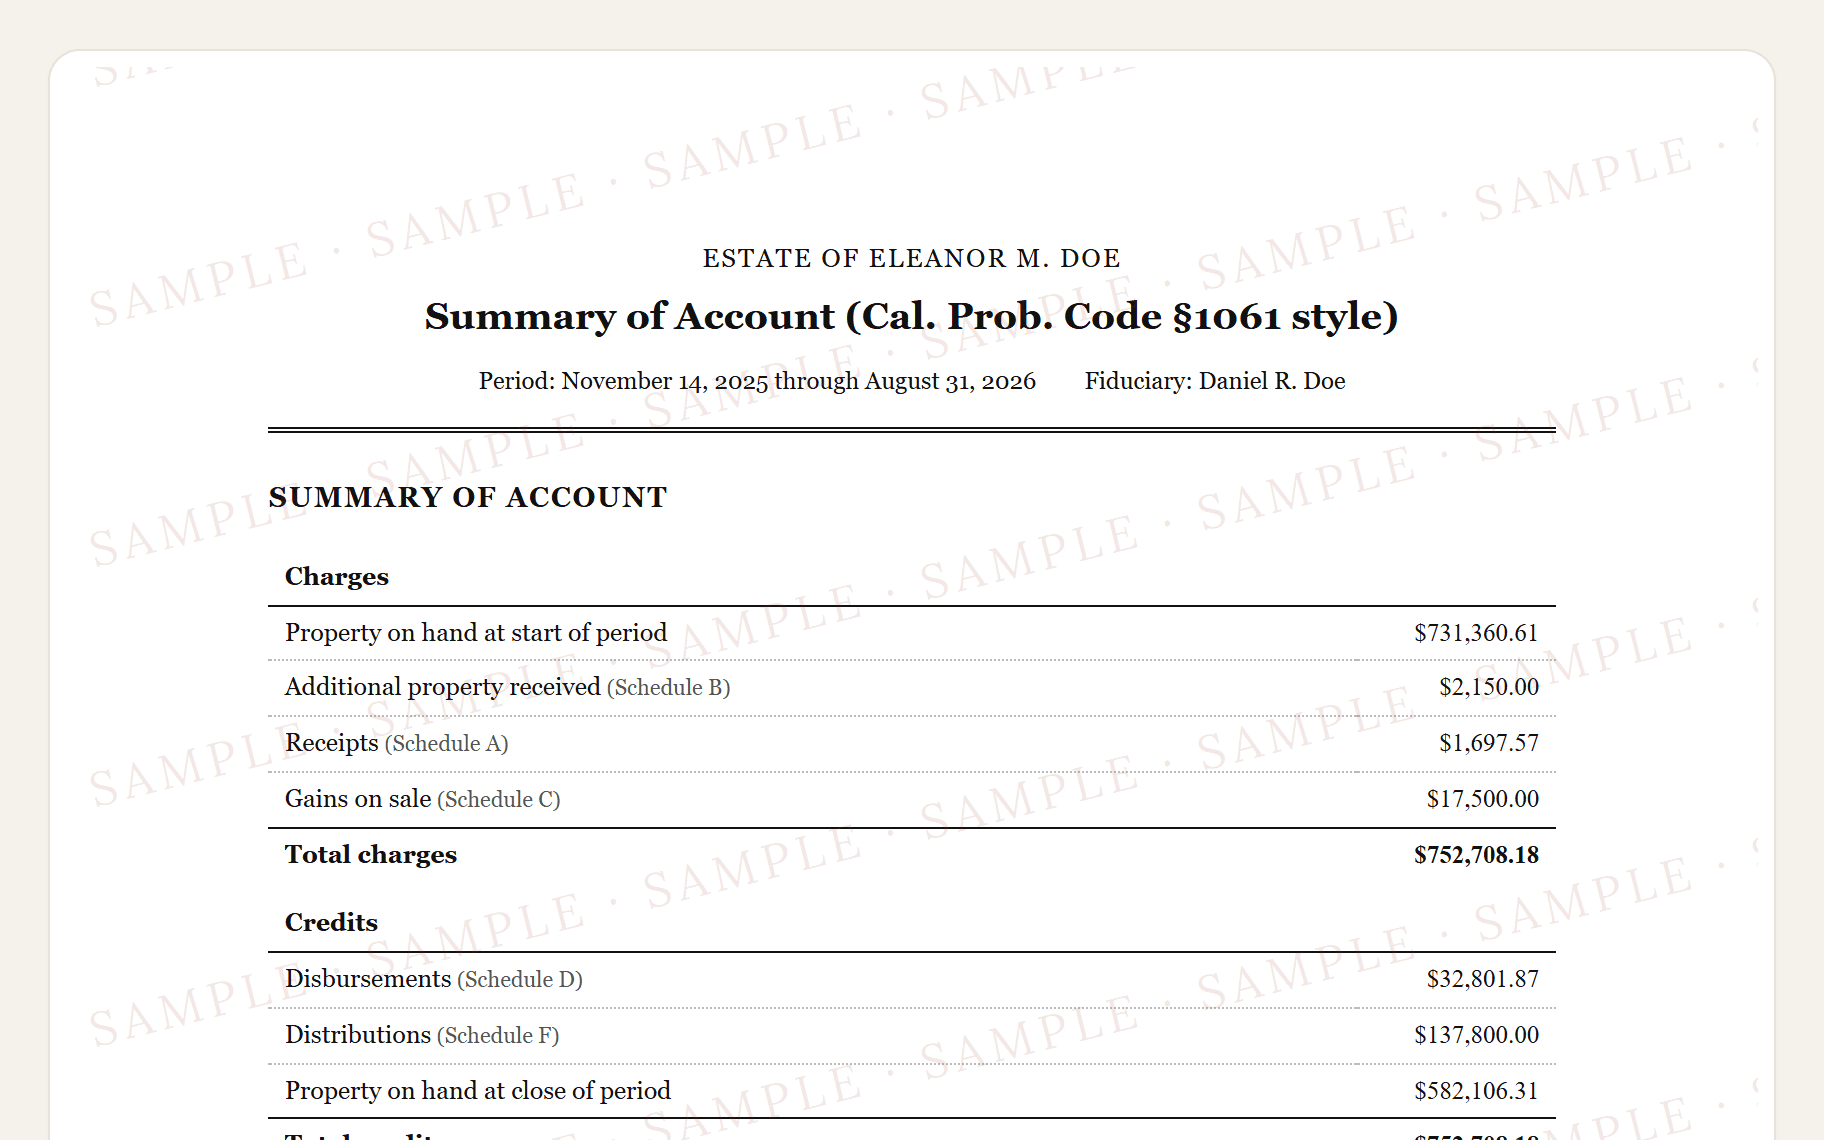
Section 1 of 7.The document California expects: the Probate Code §1061 summary
California practice expects a summary of account in the §1061 shape: cited to Probate Code §1061, balancing to the penny, with the supporting schedules behind it. ExecutorLedger produces a court-style document in that shape, not a court form, and what your court will accept is a question for the estate's attorney. Property still held is shown with a market-value column, so the reader sees what is left and what it is worth now.
That summary is built from a complete, categorized record of every dollar, ready to transcribe into the accounting filed with the petition.
Section 2 of 7.The California probate deadlines to calendar first
- Day 90 (about 3 months)Notify the California Franchise Tax Board
Why
Under Cal. Prob. Code §9202(c), the personal representative typically must give the Franchise Tax Board notice of the administration within 90 days after letters first issue; confirm with your attorney. - Day 90 (about 3 months)Notify Medi-Cal (DHCS) if the decedent got benefits
Why
Under Cal. Prob. Code §9202(a), if the decedent received (or may have received) Medi-Cal, or was the surviving spouse of someone who did, the personal representative typically must give the Department of Health Care Services notice within 90 days after letters issue (Prob. Code §215 separately requires notice within 90 days of death, an earlier deadline than this one); confirm whether this applies with your attorney. - Day 120 (about 4 months)File the inventory and appraisal with the court
Why
Under Cal. Prob. Code §8800, the inventory and appraisal is typically due within 4 months after letters issue, using a court-appointed probate referee for most assets; confirm the exact date and any extension with your attorney. - Day 120 (about 4 months)Mail notice of administration to known creditors
Why
Under Cal. Prob. Code §§9050 to 9052, notice of administration typically must reach known or reasonably ascertainable creditors within 4 months after letters issue (or within 30 days after you first learn of a creditor); confirm timing with your attorney. - Day 120 (about 4 months)Calendar the creditor claim cutoff date
Why
Under Cal. Prob. Code §9100, creditors generally must file claims by the later of 4 months after letters issue (approximated here as 120 days, which can fall up to 3 days short) or 60 days after notice was mailed to them, so calendar this bar date before paying or distributing; confirm the operative date with your attorney. - Day 365 (about 1 year)Petition to close the estate or file a status report
Why
Under Cal. Prob. Code §12200, you typically must petition for final distribution or report on the estate's status within 1 year after letters issue (18 months if a federal estate tax return is required); confirm your deadline with your attorney.
- Day 270 (about 9 months)Federal estate tax return (Form 706), if required
Why
Under IRC §6075, Form 706 is due 9 months after death, but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax; confirm applicability and timing with your attorney.
Most California dates run from the day letters issue rather than from the date of death. Nearly everything below counts forward from that day.
Read the full explanation
The inventory and appraisal is typically due within 4 months after letters issue, using a court-appointed probate referee for most assets (Cal. Prob. Code §8800). Confirm the exact date and any extension with your attorney.
Creditors get two dates. Notice of administration typically must reach known or reasonably ascertainable creditors within 4 months after letters issue, or within 30 days after you first learn of a creditor (Cal. Prob. Code §§9050 to 9052). The claim cutoff is generally the later of 4 months after letters issue or 60 days after notice was mailed to that creditor (§9100). Calendar that bar date before you pay or distribute, and confirm the operative date with your attorney.
Two more typically come due within 90 days after letters first issue. One is notice of the administration to the Franchise Tax Board (§9202(c)); confirm that one with your attorney. The other applies if the decedent received or may have received Medi-Cal, or was the surviving spouse of someone who did: notice to the Department of Health Care Services (§9202(a); Prob. Code §215 separately requires notice within 90 days of death, an earlier deadline than this one). Ask your attorney whether the Medi-Cal notice applies.
Federal Form 706 is due 9 months after death (IRC §6075), but only if the gross estate exceeds the federal exemption or the estate elects portability, and a 6-month filing extension may be available, though it does not extend the time to pay the tax. Confirm applicability and timing with your attorney. Finally, you typically must petition for final distribution, or report on the estate's status, within 1 year after letters issue, or 18 months if a federal estate tax return is required (Cal. Prob. Code §12200). Confirm that deadline with your attorney as well.
Section 3 of 7.What a California executor is paid: Probate Code §10800
California puts the number in statute. Probate Code §10800 sets marginal rates on the estate accounted for: 4% of the first $100,000, 3% of $100,000 to $200,000, 2% of $200,000 to $1,000,000, 1% of $1,000,000 to $10,000,000, and 0.5% of $10,000,000 to $25,000,000. Above $25,000,000 there is no statutory rate, and the court sets a reasonable amount.
The base is figured gross rather than net: the inventory, or appraisal, value of the probate assets, plus money received during administration, plus gains on sales, minus losses. You do not subtract the mortgage from the house first.
§10800's schedule sets the ordinary fee, and the court may reduce it when the administration ran past the time the Probate Code or the court allowed, the delay was within the executor's control, and it was not in the best interest of the estate or the people interested in it (Probate Code §12205). The court also decides when it is paid, whether extraordinary work (a house sale, litigation, tax trouble) earns more, and what is reasonable for any portion above $25,000,000. If the will sets the executor's pay, the will usually wins, so have the attorney read it. Co-executors share one fee, which the court apportions among them by the services each one rendered, or as they agree (Probate Code §10805). Executor pay is taxable income to you. Treat whatever the schedule computes as an estimate, and confirm it with the estate attorney before you take anything.
Section 4 of 7.How a California estate closes
Even the easy path goes through the courthouse. You file the petition for final distribution, either with the accounting or with waivers of account signed by every beneficiary. You attend the hearing and obtain the order for final distribution, distribute exactly as it directs, and collect receipts. Then you file those receipts with the ex parte petition for final discharge.
The waiver of account is the other route. When every beneficiary signs, no formal accounting has to go with the petition. They are giving up their right to one, though, and they still deserve a clear, complete accounting first. That is often what gets the waivers signed. If someone won't sign, or the court wants one, you are back to a full accounting in the shape the court expects. Whether the waiver route is open to you is a question for the estate's attorney.
- File the petition for final distribution, along with the accounting or signed waivers of account from every beneficiary.
- Attend the hearing and obtain the order for final distribution.
- Distribute exactly as the order directs and collect receipts.
- File the receipts and the ex parte petition for final discharge.
Section 5 of 7.What only you can supply
Software can do the bookkeeping half: every receipt and disbursement with its date, payee, and category, both sides balanced as you go, and every deadline counted from the date it runs from.
The rest is yours. The county and case number in the caption, and the fee you are requesting under §10800, come from you. The appraised values come from the probate referee. Mortgage and lien balances come from you as well: a ledger tracks what the estate owns rather than what is secured against it, so values print gross and you net them where the filing calls for it. Every judgment call belongs to the estate's attorney.
Section 6 of 7.Where ExecutorLedger fits
ExecutorLedger is California estate accounting software written for the executor rather than for a law firm. Recording is free for as long as the estate takes. Every document previews free with your real numbers: the inventory, the informal accounting beneficiaries sign, and the California court-style accounting shaped to Probate Code §1061. $149 (one-time payment) per estate lifts the watermark. Usually less than one attorney hour, and typically reimbursable by the estate. None of them is a court form. Each is a complete, correctly structured document to transcribe onto what your court expects, and your attorney reads it before anyone signs or files.
Section 7 of 7.Questions California executors ask
What is a California probate summary of account?
It is the accounting's top page: charges on one side, credits on the other, balancing to the penny, in the shape California practice expects under Probate Code §1061.
When is the California inventory and appraisal due?
Typically within 4 months after letters issue, using a court-appointed probate referee for most assets (Cal. Prob. Code §8800). Confirm the exact date and any extension with your attorney.
How much is the executor fee in California?
Probate Code §10800 sets it by schedule: 4% of the first $100,000, 3% of $100,000 to $200,000, 2% of $200,000 to $1,000,000, 1% of $1,000,000 to $10,000,000, and 0.5% of $10,000,000 to $25,000,000, with anything above $25,000,000 left to the court. The base is appraisal value plus receipts plus gains minus losses, gross. §10800's schedule sets the ordinary fee, and the court may reduce it when the administration ran past the time the Probate Code or the court allowed, the delay was within the executor's control, and it was not in the best interest of the estate or the people interested in it (Probate Code §12205). The portion above $25,000,000 has no statutory rate. If the will sets the pay, the will usually wins. Confirm the figure with the estate attorney.
Do I have to file a final accounting in California probate?
Not always. The petition for final distribution can go in with the accounting, or with waivers of account signed by every beneficiary. Either way a petition is filed, a hearing is held, and an order for final distribution authorizes you to distribute. You typically must petition, or report on the estate's status, within 1 year after letters issue, or 18 months if a federal estate tax return is required (Cal. Prob. Code §12200); confirm your deadline with your attorney.
Is there a California accounting form I can download and fill in?
What you need is a complete, balanced record in the §1061 shape. ExecutorLedger produces a court-style California accounting shaped to Probate Code §1061, ready to transcribe onto whatever your court requires. It is a court-style document, not a court form, and the estate's attorney confirms what your court expects.
Not sure which accounting your situation calls for? Which accounting do I need? covers the choice, and the accounting guide explains the structure every format shares.
This page describes California practice as our verified references state it; formats drift and estates differ, and none of this is legal advice. ExecutorLedger produces court-style documents for transcription. They are not official court forms. The accounting your estate needs is a question for its attorney.